Disclosure: Card terms, credits and earning rates change often, and this is not financial advice. Figures below are as of November 2026; check the issuer’s page before you apply. This post may contain affiliate links. See our disclosure page for details.
A $14 bacon, egg and cheese with coffee on a Tuesday. A $68 dinner for two at the Thai place on the corner on Thursday. A $38 Seamless order on a rainy Sunday. None of these feels like “dining spend,” but in New York they add up fast, often to $500–$900 a month before groceries. That everyday pattern, not the once-a-year tasting menu, is what decides the best dining credit card NYC for most people.
This guide compares the two cards New Yorkers ask me about most, the American Express Gold Card and the Chase Sapphire Reserve, strictly on ordinary eating: neighborhood restaurants, takeout, coffee and the weekly grocery run. If you want the splurge side, I’ve covered Michelin dining and the Resy credit separately, and the Reserve’s Exclusive Tables credit and city-life perks have their own post.
Quick Answer: Amex Gold vs Sapphire Reserve Dining
- For everyday eating, the Amex Gold usually wins. It earns 4x at restaurants (up to $50,000 a year) and 4x at U.S. supermarkets (up to $25,000), against the Reserve’s 3x dining and 1x groceries.
- The fee gap is $470. Gold is $325 a year; the Reserve is $795 (as of November 2026).
- The Gold’s credits fit an NYC routine (Uber Cash, Seamless/Grubhub, Resy), and a regular user can roughly cover the fee with them.
- The Reserve is a travel card that happens to earn well on dining. Its case rests on the $300 travel credit, lounges and hotel credits, not on restaurant points.
- If you already hold the Reserve, adding the Gold for food is close to fee-neutral if you use its credits, and it lifts grocery earning from 1x to 4x.
The Two Cards at a Glance (As of November 2026)
The table below sticks to what matters at a dinner table or a checkout line. Earning rates and credits come from American Express’s Gold Card page and Chase’s Sapphire Reserve page.
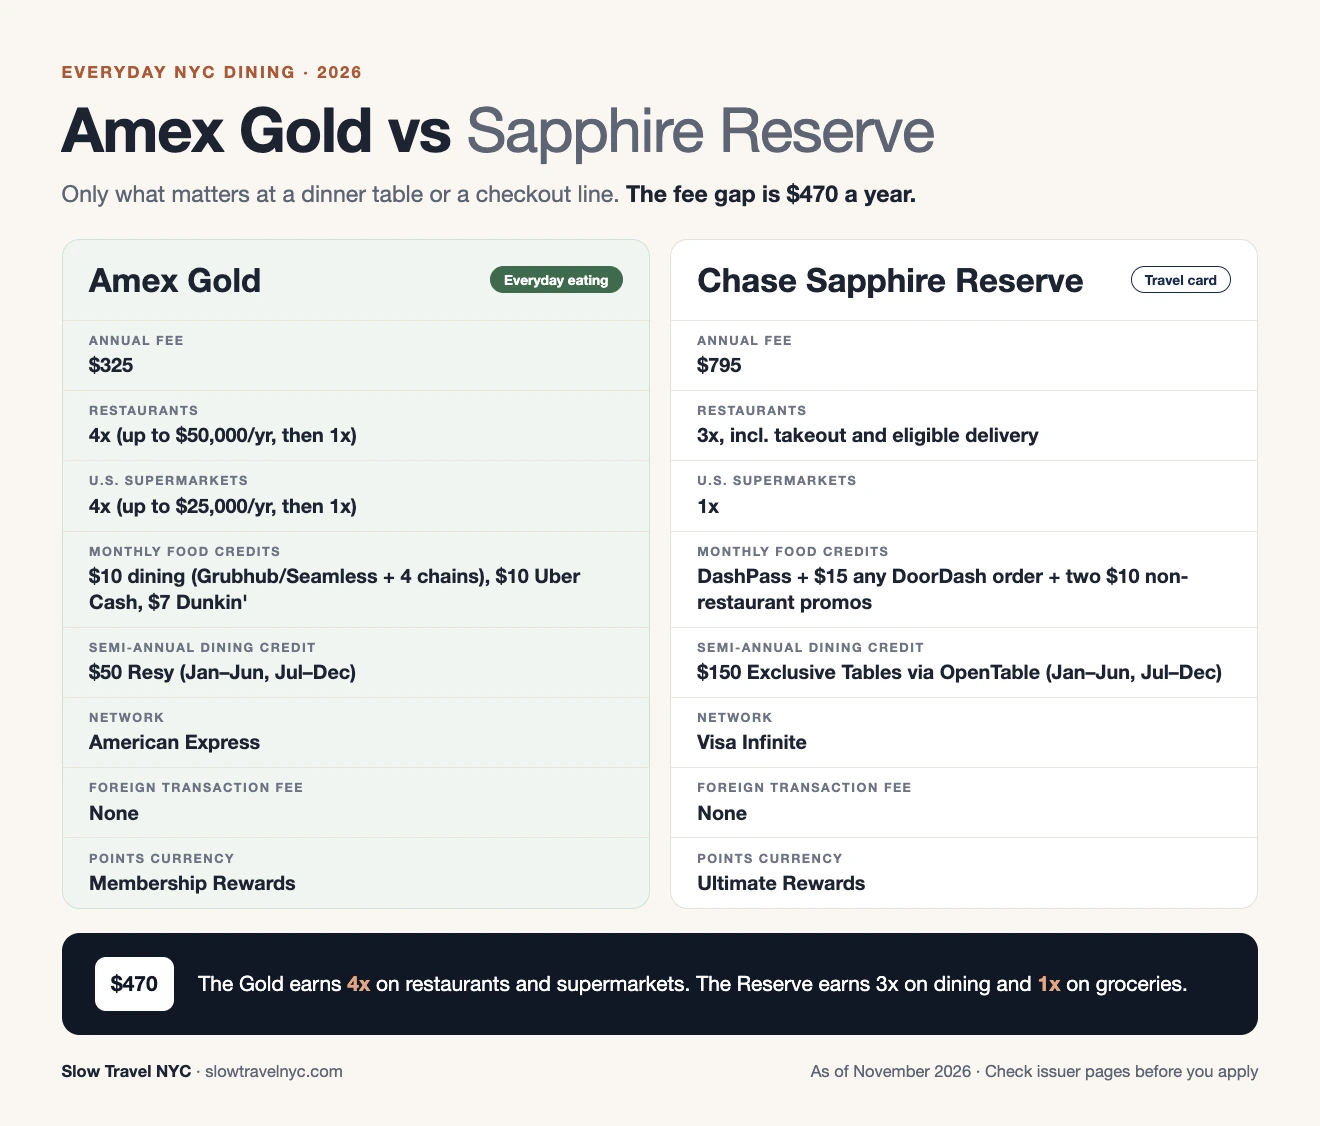
Two details are easy to miss. First, the Gold’s $10 monthly dining credit only works at its named partners; after an April 2026 refresh those are Grubhub (including Seamless), The Cheesecake Factory, Five Guys, Buffalo Wild Wings and Wonder, per Amex’s dining guide. Second, Chase raised the Reserve’s DoorDash restaurant credit from $5 to $15 a month starting October 1, 2026, and it now works on any eligible order (Chase’s announcement).
Everyday NYC Dining Math: Three Real Eating Patterns
Points tables flatter whichever card has the bigger number. A better test is to run each card against how people in this city actually eat. Here is how the Amex Gold vs Sapphire Reserve dining comparison plays out across three common New York patterns, using annual spend and each card’s base earning rates.
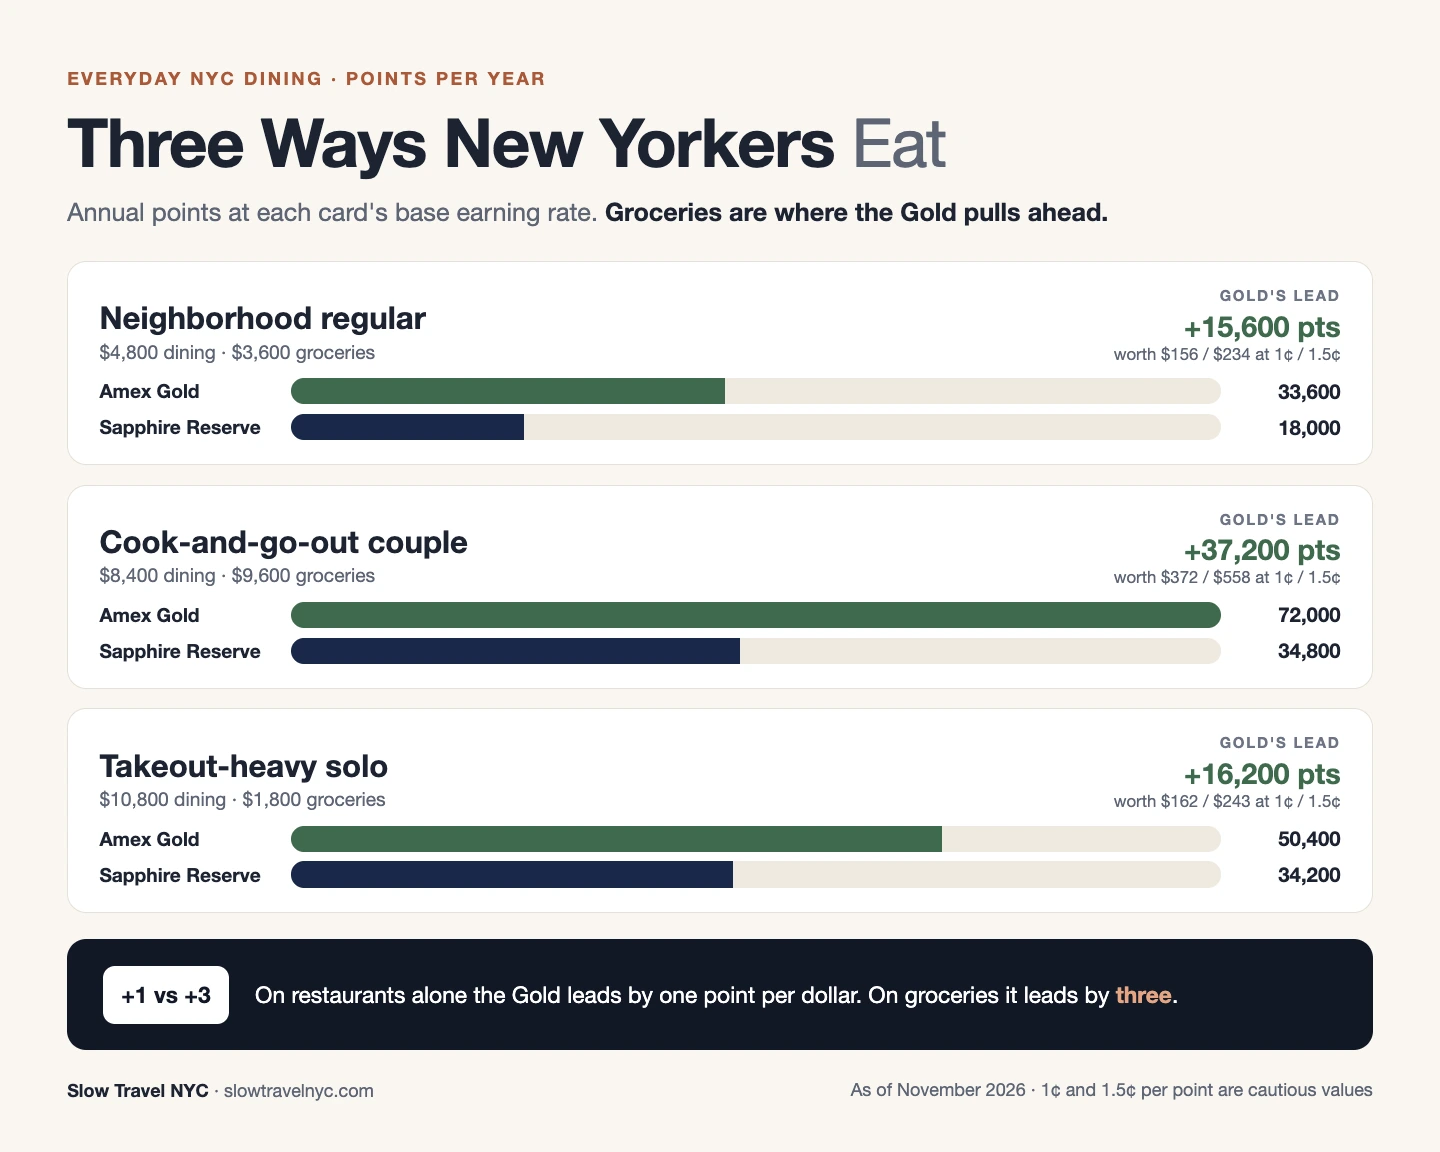
The pattern is clear once you look at where the gap comes from. On restaurants alone, the Gold is ahead by only one point per dollar. On groceries, it is ahead by three, so the household that cooks at home gets most of the benefit. If your fridge holds little more than oat milk and hot sauce, the two cards are closer than the 4x headline suggests.
A note on the point values: 1 to 1.5 cents per point is a cautious range for either currency. You can do better by transferring to airline partners, and worse by cashing out. Since June 2025, the Reserve’s fixed 1.5-cent portal rate has been replaced by variable “Points Boost” pricing, with older points grandfathered through October 26, 2027, as One Mile at a Time explains.
Don’t forget tax and tip
In New York, your card is charged for the tip and the 8.875% sales tax along with the food, and both earn points. An $80 dinner becomes about $103 after tax and a 20% tip, which is roughly 412 Gold points versus 309 Reserve points. Our NYC Tip & Tax Calculator gives you the real total before you pay.
Credits That Fit a New York Routine
Statement credits only count if you’d spend the money anyway. Here is how each card’s food-related credits line up with an ordinary NYC month.
Amex Gold: small, monthly and urban
The Gold’s credits are built for a city like this one. Uber Cash ($10 a month) covers a short ride or part of an Uber Eats order. Seamless, which many New Yorkers already use, triggers the $10 dining credit. The $50 Resy credit each half-year is easy to use here, because a large share of the city’s sit-down restaurants are on Resy. You don’t have to book through the app; you just pay with the card at a participating restaurant.
The Dunkin’ credit ($7 a month) is real money only if Dunkin’ is already part of your morning. Mine is a slow pour-over at a café where time actually slows down, so I’d count that one as zero.
Sapphire Reserve: bigger numbers, more structure
The Reserve’s food credits look larger on paper. With DashPass activated, you get a $15 monthly promo on any eligible DoorDash order plus two $10 promos for grocery or convenience orders. If you already order through DoorDash, that’s up to $420 a year. The $300 Exclusive Tables credit ($150 per half-year) is real too, but it applies only to participating restaurants on OpenTable, which lean toward special-occasion spots rather than the corner Thai place.
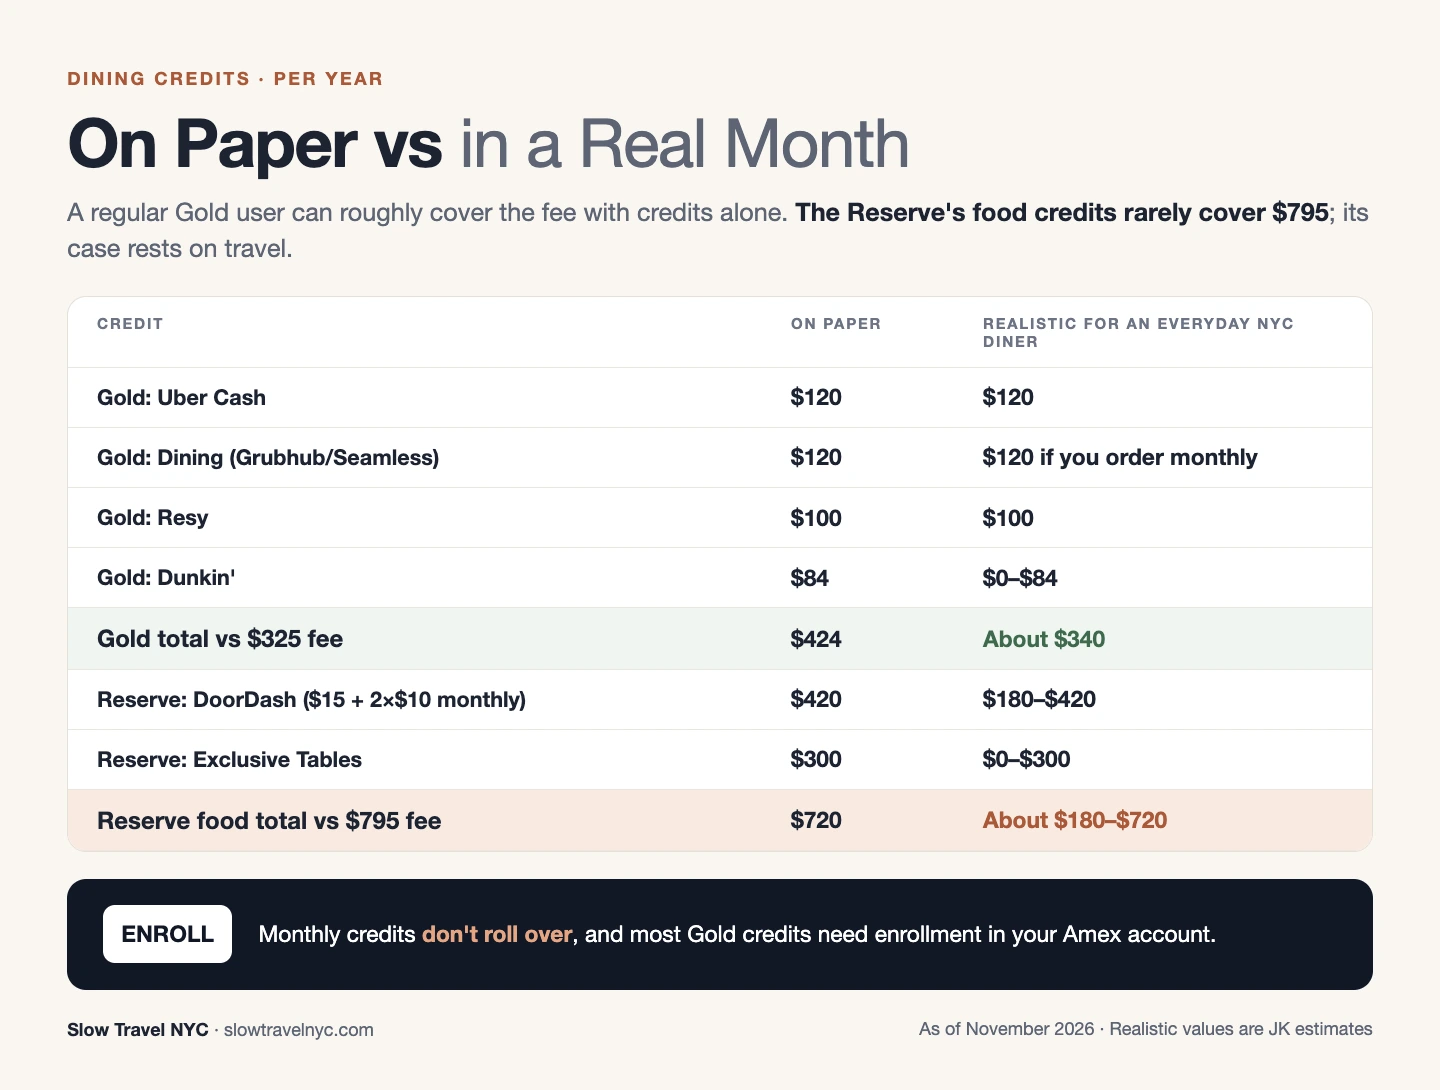
Read that bottom line carefully. A regular Gold user can roughly cover the fee with the credits alone. The Reserve’s food credits rarely cover a $795 fee by themselves, which is why its value case depends on the $300 travel credit, lounges and hotel credits. I’ve weighed those separately in our NYC airport lounge credit card guide.
Which Card Fits How You Actually Eat
There is no single winner for everyone, so here is a plain sorting.
Choose the Amex Gold if:
- You cook several nights a week and shop at supermarkets like Trader Joe’s or Whole Foods.
- You already use Uber, Seamless or Resy-listed restaurants.
- You want strong dining earning without paying for lounges you rarely visit.
Choose the Sapphire Reserve if:
- You fly several times a year and will use the $300 travel credit, lounge access and hotel credits.
- You already order through DoorDash every month.
- You’d rather hold one Visa that works nearly everywhere, at home and abroad.
Consider both if: you already hold the Reserve for travel. Adding the Gold for food costs $325, which the credits can roughly offset, and it moves your grocery spend from 1x to 4x. The trade-off is managing two point programs and a handful of monthly credits.
Consider neither if: dining is your only goal and you’d skip most credits. The Chase Sapphire Preferred earns the same 3x on dining as the Reserve for a $95 annual fee (as of November 2026), and a no-annual-fee card may suit a lighter spender better.
Reality Check: The Catches
Every premium card asks for something back. Here is what to weigh before you apply.
- Amex acceptance still has gaps. Most NYC restaurants take Amex, but some small cafés, bakeries and food stalls don’t, and a few are cash-only. Carry a Visa or Mastercard backup. Visitors can see our no-foreign-transaction-fee card guide.
- Merchant coding decides your points. A restaurant inside a hotel may code as lodging. A deli or bodega may code as convenience, not as a supermarket or restaurant. Amex also excludes superstores and warehouse clubs from 4x groceries. Check your first few statements.
- Monthly credits expire. Gold’s dining, Uber and Dunkin’ credits reset every month and don’t roll over. Miss January, and that $10 is gone. Most of the Gold credits also require enrollment in your Amex account.
- Credits shape behavior. A $10 Five Guys credit is only “value” if you’d have eaten there anyway. Ordering delivery to use a promo can cost more than it saves after fees and tip.
- The 4x caps exist. They’re generous ($50,000 dining, $25,000 groceries a year), but heavy business-dining spenders can hit them.
- Point values move. Chase’s switch to Points Boost and Amex’s history of rotating dining partners are reminders that the math above can change within a year.
How I’d Decide, Slowly
Before choosing, pull three months of statements and sort them into three buckets: restaurants and takeout, supermarkets, and travel. It takes about twenty minutes with a coffee, and it answers the question better than any comparison table, including mine.
If groceries are a meaningful bucket, the Amex Gold is likely the better daily dining card. If travel is the biggest bucket and dining is a close second, the Reserve earns its keep elsewhere and its 3x dining is a solid bonus. Either way, look at the fee you’ll pay against the credits you’d truly use in an ordinary month, not an ideal one.
FAQ
What is the best dining credit card in NYC for everyday meals?
For most New Yorkers who eat out and cook, the Amex Gold is the strongest everyday option as of November 2026. It earns 4x at restaurants and U.S. supermarkets, and its Uber, Seamless and Resy credits fit a city routine. Frequent travelers may still prefer the Sapphire Reserve for its travel benefits.
Does the Amex Gold earn 4x on takeout and delivery?
Amex’s terms count takeout and delivery from U.S. restaurants in the 4x restaurant category. Orders through a delivery app usually code as dining, but coding depends on the merchant, so check your statement after your first few orders.
Is the Sapphire Reserve worth $795 just for dining?
Rarely. Its 3x dining rate is good, but the Sapphire Preferred earns the same 3x for $95. The Reserve’s fee makes sense when you’ll use its travel credit, lounge access and hotel credits as well.
Can I use the Amex Gold Resy credit at any NYC restaurant?
No. It applies only at participating U.S. restaurants listed on Resy, up to $50 from January to June and $50 from July to December. Enrollment is required, and you don’t need to book through Resy to receive it.
Should I hold both the Amex Gold and the Sapphire Reserve?
It can make sense if you already have the Reserve for travel. Use the Gold for restaurants and groceries and the Reserve for travel and places that don’t take Amex. The combined fee is $1,120 a year, so it only works if you use most of both cards’ credits.
The Bottom Line: The Best Dining Credit Card NYC Pick
The best dining card is the one that matches the meals you already eat. For most New Yorkers, that’s the Amex Gold: 4x where the money actually goes, a $325 fee that its city-friendly credits can cover, and no pressure to eat differently. The Sapphire Reserve remains an excellent card, but its case is mostly made at the airport, not at your neighborhood restaurant.
Planning a visit around food? Our NYC Trip Budget Calculator helps you estimate dining costs before you go.