Best Dining Credit Card NYC (2026): Amex Gold vs Sapphire Reserve for Everyday Eating

Looking for the best dining credit card NYC locals can actually use? We run Amex Gold vs Sapphire Reserve dining math on three real New York eating patterns, including groceries, takeout, tax and tip.

Latte in a dark cup on a wooden café table beside a window and a folded newspaper

Disclosure: Card terms, credits and earning rates change often, and this is not financial advice. Figures below are as of November 2026; check the issuer’s page before you apply. This post may contain affiliate links. See our disclosure page for details.

A $14 bacon, egg and cheese with coffee on a Tuesday. A $68 dinner for two at the Thai place on the corner on Thursday. A $38 Seamless order on a rainy Sunday. None of these feels like “dining spend,” but in New York they add up fast, often to $500–$900 a month before groceries. That everyday pattern, not the once-a-year tasting menu, is what decides the best dining credit card NYC for most people.

This guide compares the two cards New Yorkers ask me about most, the American Express Gold Card and the Chase Sapphire Reserve, strictly on ordinary eating: neighborhood restaurants, takeout, coffee and the weekly grocery run. If you want the splurge side, I’ve covered Michelin dining and the Resy credit separately, and the Reserve’s Exclusive Tables credit and city-life perks have their own post.

Quick Answer: Amex Gold vs Sapphire Reserve Dining

  • For everyday eating, the Amex Gold usually wins. It earns 4x at restaurants (up to $50,000 a year) and 4x at U.S. supermarkets (up to $25,000), against the Reserve’s 3x dining and 1x groceries.
  • The fee gap is $470. Gold is $325 a year; the Reserve is $795 (as of November 2026).
  • The Gold’s credits fit an NYC routine (Uber Cash, Seamless/Grubhub, Resy), and a regular user can roughly cover the fee with them.
  • The Reserve is a travel card that happens to earn well on dining. Its case rests on the $300 travel credit, lounges and hotel credits, not on restaurant points.
  • If you already hold the Reserve, adding the Gold for food is close to fee-neutral if you use its credits, and it lifts grocery earning from 1x to 4x.

The Two Cards at a Glance (As of November 2026)

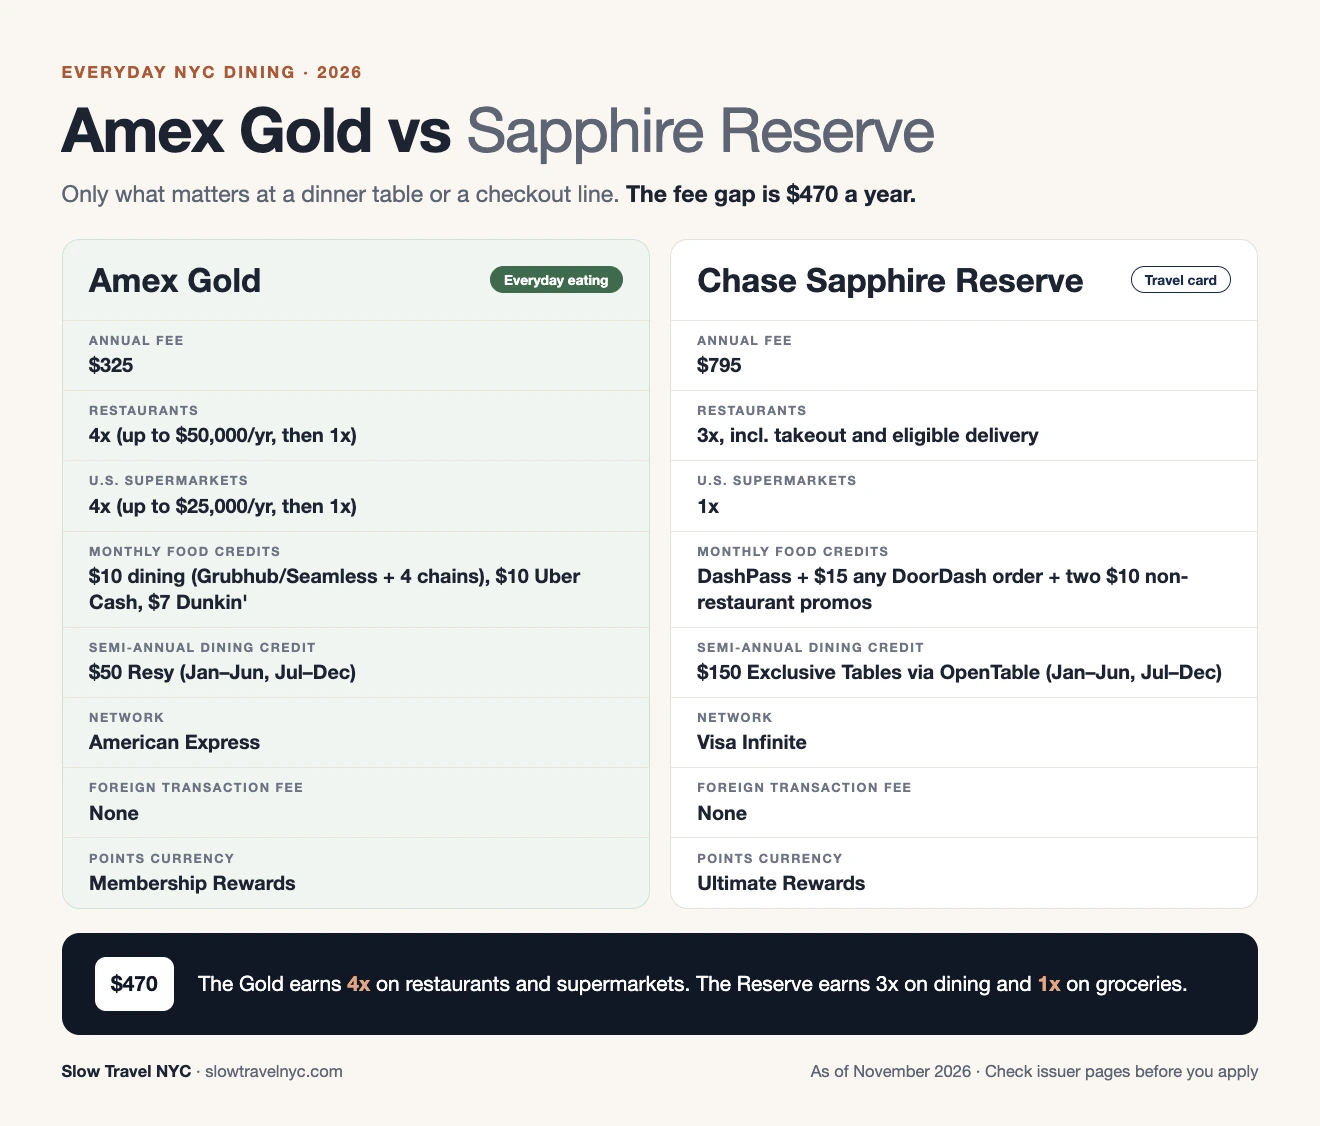
The table below sticks to what matters at a dinner table or a checkout line. Earning rates and credits come from American Express’s Gold Card page and Chase’s Sapphire Reserve page.
best dining credit card nyc

Two details are easy to miss. First, the Gold’s $10 monthly dining credit only works at its named partners; after an April 2026 refresh those are Grubhub (including Seamless), The Cheesecake Factory, Five Guys, Buffalo Wild Wings and Wonder, per Amex’s dining guide. Second, Chase raised the Reserve’s DoorDash restaurant credit from $5 to $15 a month starting October 1, 2026, and it now works on any eligible order (Chase’s announcement).

Everyday NYC Dining Math: Three Real Eating Patterns

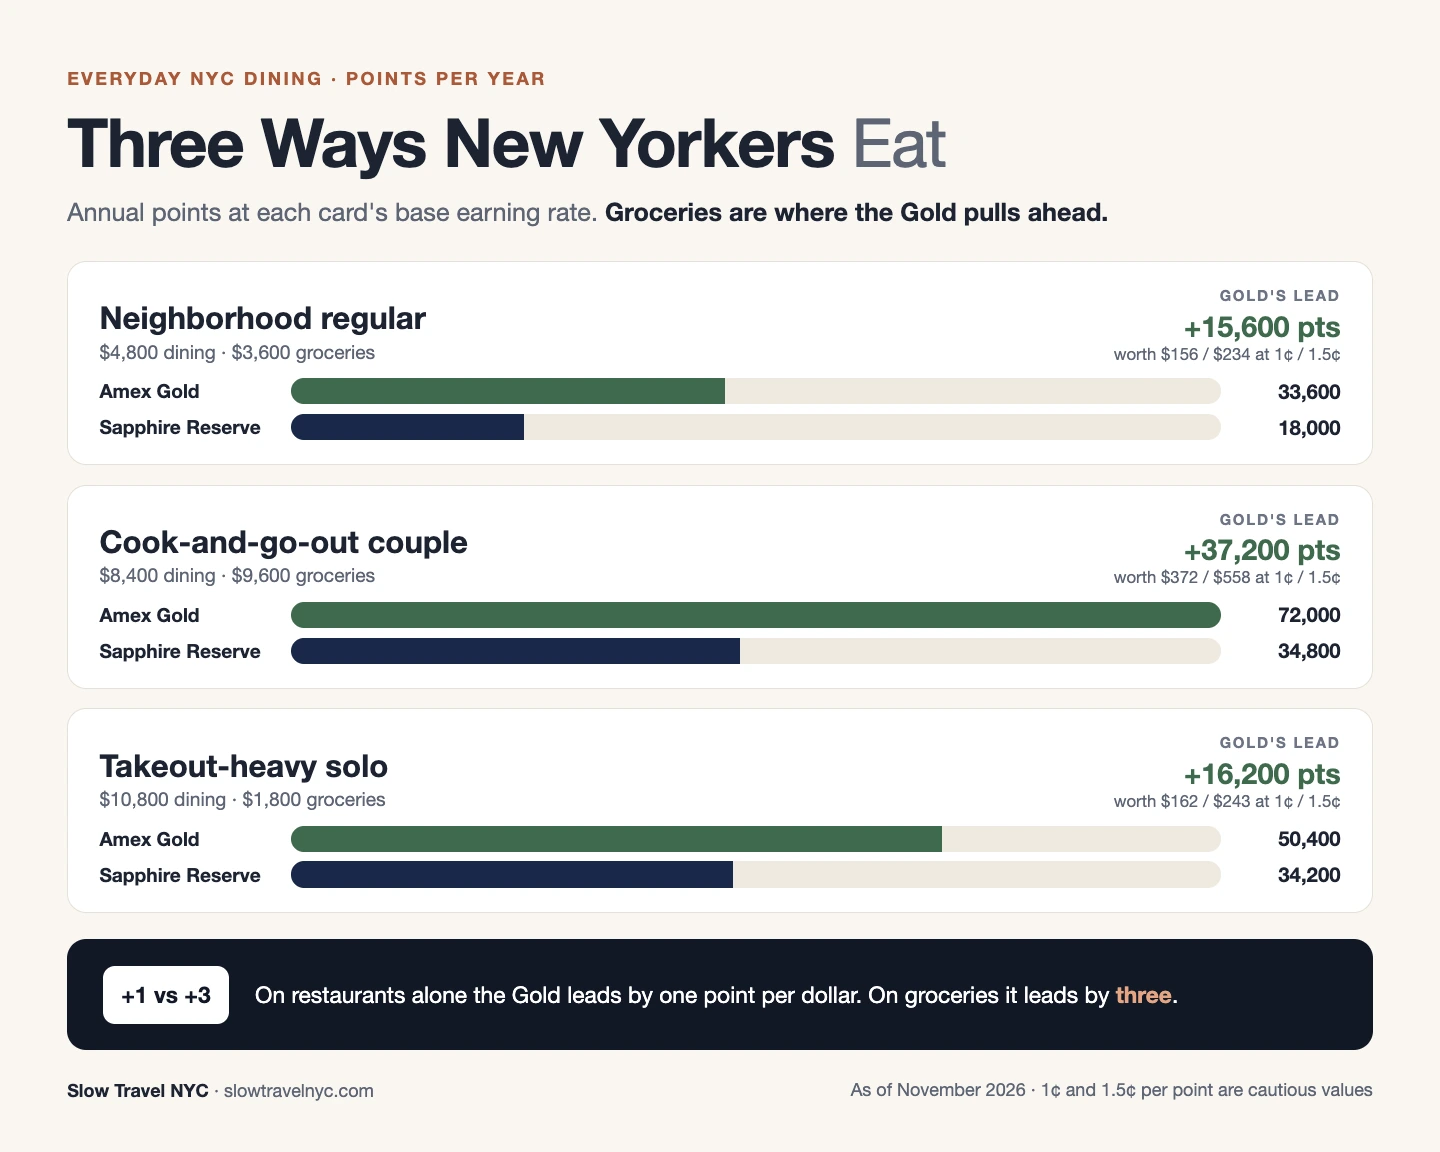
Points tables flatter whichever card has the bigger number. A better test is to run each card against how people in this city actually eat. Here is how the Amex Gold vs Sapphire Reserve dining comparison plays out across three common New York patterns, using annual spend and each card’s base earning rates.
Bar chart of annual points earned by Amex Gold and Sapphire Reserve across three New York eating patterns

The pattern is clear once you look at where the gap comes from. On restaurants alone, the Gold is ahead by only one point per dollar. On groceries, it is ahead by three, so the household that cooks at home gets most of the benefit. If your fridge holds little more than oat milk and hot sauce, the two cards are closer than the 4x headline suggests.

A note on the point values: 1 to 1.5 cents per point is a cautious range for either currency. You can do better by transferring to airline partners, and worse by cashing out. Since June 2025, the Reserve’s fixed 1.5-cent portal rate has been replaced by variable “Points Boost” pricing, with older points grandfathered through October 26, 2027, as One Mile at a Time explains.

Don’t forget tax and tip

In New York, your card is charged for the tip and the 8.875% sales tax along with the food, and both earn points. An $80 dinner becomes about $103 after tax and a 20% tip, which is roughly 412 Gold points versus 309 Reserve points. Our NYC Tip & Tax Calculator gives you the real total before you pay.

Credits That Fit a New York Routine
A food delivery cyclist with a green insulated bag riding through a rainy city street at night

Statement credits only count if you’d spend the money anyway. Here is how each card’s food-related credits line up with an ordinary NYC month.

Amex Gold: small, monthly and urban

The Gold’s credits are built for a city like this one. Uber Cash ($10 a month) covers a short ride or part of an Uber Eats order. Seamless, which many New Yorkers already use, triggers the $10 dining credit. The $50 Resy credit each half-year is easy to use here, because a large share of the city’s sit-down restaurants are on Resy. You don’t have to book through the app; you just pay with the card at a participating restaurant.

The Dunkin’ credit ($7 a month) is real money only if Dunkin’ is already part of your morning. Mine is a slow pour-over at a café where time actually slows down, so I’d count that one as zero.

Sapphire Reserve: bigger numbers, more structure

The Reserve’s food credits look larger on paper. With DashPass activated, you get a $15 monthly promo on any eligible DoorDash order plus two $10 promos for grocery or convenience orders. If you already order through DoorDash, that’s up to $420 a year. The $300 Exclusive Tables credit ($150 per half-year) is real too, but it applies only to participating restaurants on OpenTable, which lean toward special-occasion spots rather than the corner Thai place.
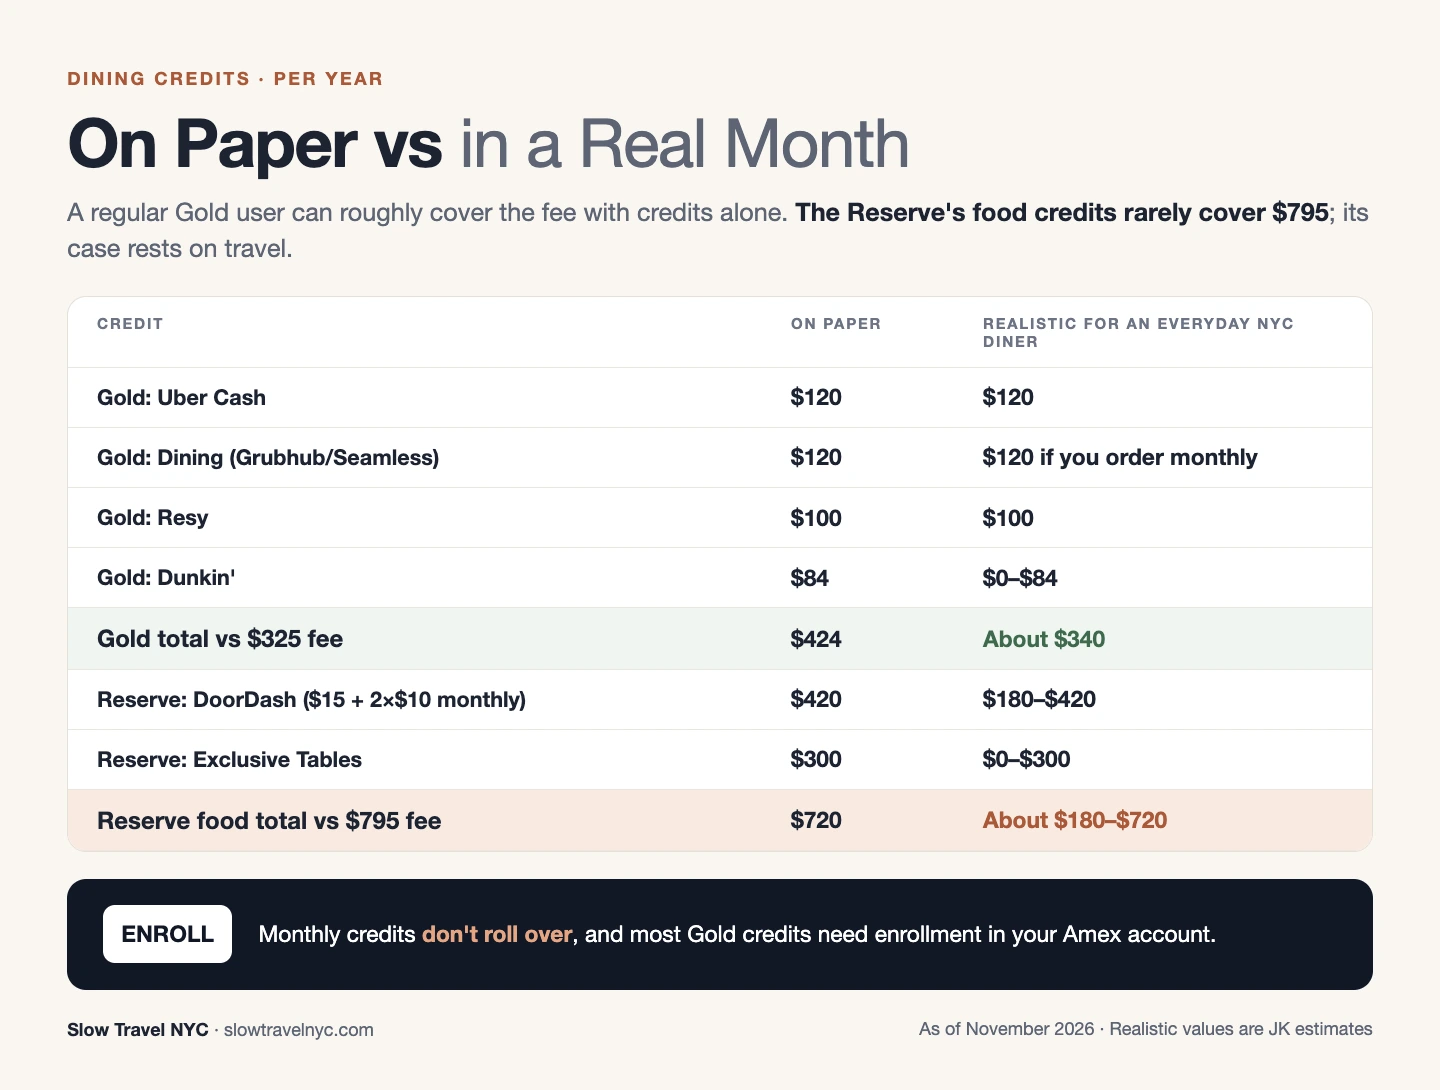
Table graphic showing on-paper versus realistic annual value of Amex Gold and Sapphire Reserve dining credits

Read that bottom line carefully. A regular Gold user can roughly cover the fee with the credits alone. The Reserve’s food credits rarely cover a $795 fee by themselves, which is why its value case depends on the $300 travel credit, lounges and hotel credits. I’ve weighed those separately in our NYC airport lounge credit card guide.

Which Card Fits How You Actually Eat

There is no single winner for everyone, so here is a plain sorting.

Choose the Amex Gold if:

  • You cook several nights a week and shop at supermarkets like Trader Joe’s or Whole Foods.
  • You already use Uber, Seamless or Resy-listed restaurants.
  • You want strong dining earning without paying for lounges you rarely visit.

Choose the Sapphire Reserve if:

  • You fly several times a year and will use the $300 travel credit, lounge access and hotel credits.
  • You already order through DoorDash every month.
  • You’d rather hold one Visa that works nearly everywhere, at home and abroad.

Consider both if: you already hold the Reserve for travel. Adding the Gold for food costs $325, which the credits can roughly offset, and it moves your grocery spend from 1x to 4x. The trade-off is managing two point programs and a handful of monthly credits.

Consider neither if: dining is your only goal and you’d skip most credits. The Chase Sapphire Preferred earns the same 3x on dining as the Reserve for a $95 annual fee (as of November 2026), and a no-annual-fee card may suit a lighter spender better.

Reality Check: The Catches
A person tapping a credit card on a handheld payment terminal beside a latte on a café table

Every premium card asks for something back. Here is what to weigh before you apply.

  • Amex acceptance still has gaps. Most NYC restaurants take Amex, but some small cafés, bakeries and food stalls don’t, and a few are cash-only. Carry a Visa or Mastercard backup. Visitors can see our no-foreign-transaction-fee card guide.
  • Merchant coding decides your points. A restaurant inside a hotel may code as lodging. A deli or bodega may code as convenience, not as a supermarket or restaurant. Amex also excludes superstores and warehouse clubs from 4x groceries. Check your first few statements.
  • Monthly credits expire. Gold’s dining, Uber and Dunkin’ credits reset every month and don’t roll over. Miss January, and that $10 is gone. Most of the Gold credits also require enrollment in your Amex account.
  • Credits shape behavior. A $10 Five Guys credit is only “value” if you’d have eaten there anyway. Ordering delivery to use a promo can cost more than it saves after fees and tip.
  • The 4x caps exist. They’re generous ($50,000 dining, $25,000 groceries a year), but heavy business-dining spenders can hit them.
  • Point values move. Chase’s switch to Points Boost and Amex’s history of rotating dining partners are reminders that the math above can change within a year.

How I’d Decide, Slowly

Before choosing, pull three months of statements and sort them into three buckets: restaurants and takeout, supermarkets, and travel. It takes about twenty minutes with a coffee, and it answers the question better than any comparison table, including mine.

If groceries are a meaningful bucket, the Amex Gold is likely the better daily dining card. If travel is the biggest bucket and dining is a close second, the Reserve earns its keep elsewhere and its 3x dining is a solid bonus. Either way, look at the fee you’ll pay against the credits you’d truly use in an ordinary month, not an ideal one.

FAQ

What is the best dining credit card in NYC for everyday meals?

For most New Yorkers who eat out and cook, the Amex Gold is the strongest everyday option as of November 2026. It earns 4x at restaurants and U.S. supermarkets, and its Uber, Seamless and Resy credits fit a city routine. Frequent travelers may still prefer the Sapphire Reserve for its travel benefits.

Does the Amex Gold earn 4x on takeout and delivery?

Amex’s terms count takeout and delivery from U.S. restaurants in the 4x restaurant category. Orders through a delivery app usually code as dining, but coding depends on the merchant, so check your statement after your first few orders.

Is the Sapphire Reserve worth $795 just for dining?

Rarely. Its 3x dining rate is good, but the Sapphire Preferred earns the same 3x for $95. The Reserve’s fee makes sense when you’ll use its travel credit, lounge access and hotel credits as well.

Can I use the Amex Gold Resy credit at any NYC restaurant?

No. It applies only at participating U.S. restaurants listed on Resy, up to $50 from January to June and $50 from July to December. Enrollment is required, and you don’t need to book through Resy to receive it.

Should I hold both the Amex Gold and the Sapphire Reserve?

It can make sense if you already have the Reserve for travel. Use the Gold for restaurants and groceries and the Reserve for travel and places that don’t take Amex. The combined fee is $1,120 a year, so it only works if you use most of both cards’ credits.

The Bottom Line: The Best Dining Credit Card NYC Pick

The best dining card is the one that matches the meals you already eat. For most New Yorkers, that’s the Amex Gold: 4x where the money actually goes, a $325 fee that its city-friendly credits can cover, and no pressure to eat differently. The Sapphire Reserve remains an excellent card, but its case is mostly made at the airport, not at your neighborhood restaurant.

Planning a visit around food? Our NYC Trip Budget Calculator helps you estimate dining costs before you go.
Related Reading

Chase Sapphire Reserve for NYC Residents (2026): Is $795 Worth It Without the Lounges?

Is the Chase Sapphire Reserve for NYC residents worth $795 if you rarely use airport lounges? Here’s each local credit priced at what a New Yorker would actually spend, plus three break-even profiles.

Hands, a coffee mug, a card reader, a tablet and a phone on a wooden table seen from above

Disclosure: Card terms change often, and this is not financial advice. Figures are as of November 2026 and come from Chase’s public card page unless noted. Some links on this site may be affiliate links; see our disclosure policy.

Seven hundred ninety-five dollars works out to about $66 a month, or roughly 22 subway rides at the $3 base fare. It is also the annual fee on the Chase Sapphire Reserve, and that number is why so many people are now asking whether the Chase Sapphire Reserve for NYC residents still makes sense once the welcome bonus is spent.

Most reviews answer that question from an airport. This one stays in the city. The lounges are real, but if you live here, the question is whether the Sapphire Reserve credits in NYC fit the way you already eat, move, and spend your evenings in New York. I’ve written separately about NYC airport lounge credit cards, so lounges get one paragraph here and the rest of the page goes to the credits you’d use at home.

Quick Answer

  • The fee: $795 a year, plus $195 per authorized user (as of November 2026).
  • The easy money: The $300 travel credit is the most flexible piece for a New Yorker. Chase’s travel category includes taxis, ferries, tolls, parking garages, and passenger trains.
  • The conditional money: The $300 dining credit only works at roughly 30 NYC restaurants on Chase’s Exclusive Tables list, split into two $150 halves.
  • The habit money: DoorDash, Lyft, Peloton, StubHub, and Apple credits only count if you’d pay for those services anyway.
  • The verdict: If you’d naturally use the travel credit, both dining halves, and most of the DoorDash promos, you’re close to break-even before lounges. If not, the $95 Sapphire Preferred is the calmer choice.
  • Deadline: The July–December dining and StubHub halves, and the 2026-only $250 hotel credit, all expire December 31, 2026.

What the $795 Actually Buys (As of November 2026)

Chase markets the card as delivering “$3,000+ in annual value.” That figure assumes you use nearly every credit, every month, at full face value. The useful exercise is to price each credit at what it would replace in your own budget, not at the number on the brochure.

The card earns 8x points on Chase Travel purchases, 4x on flights and hotels booked direct, 3x on dining worldwide, and 1x on everything else, according to the Chase Sapphire Reserve card page. Points are part of the story, but for a resident who mostly spends locally, the statement credits do the heavy lifting.

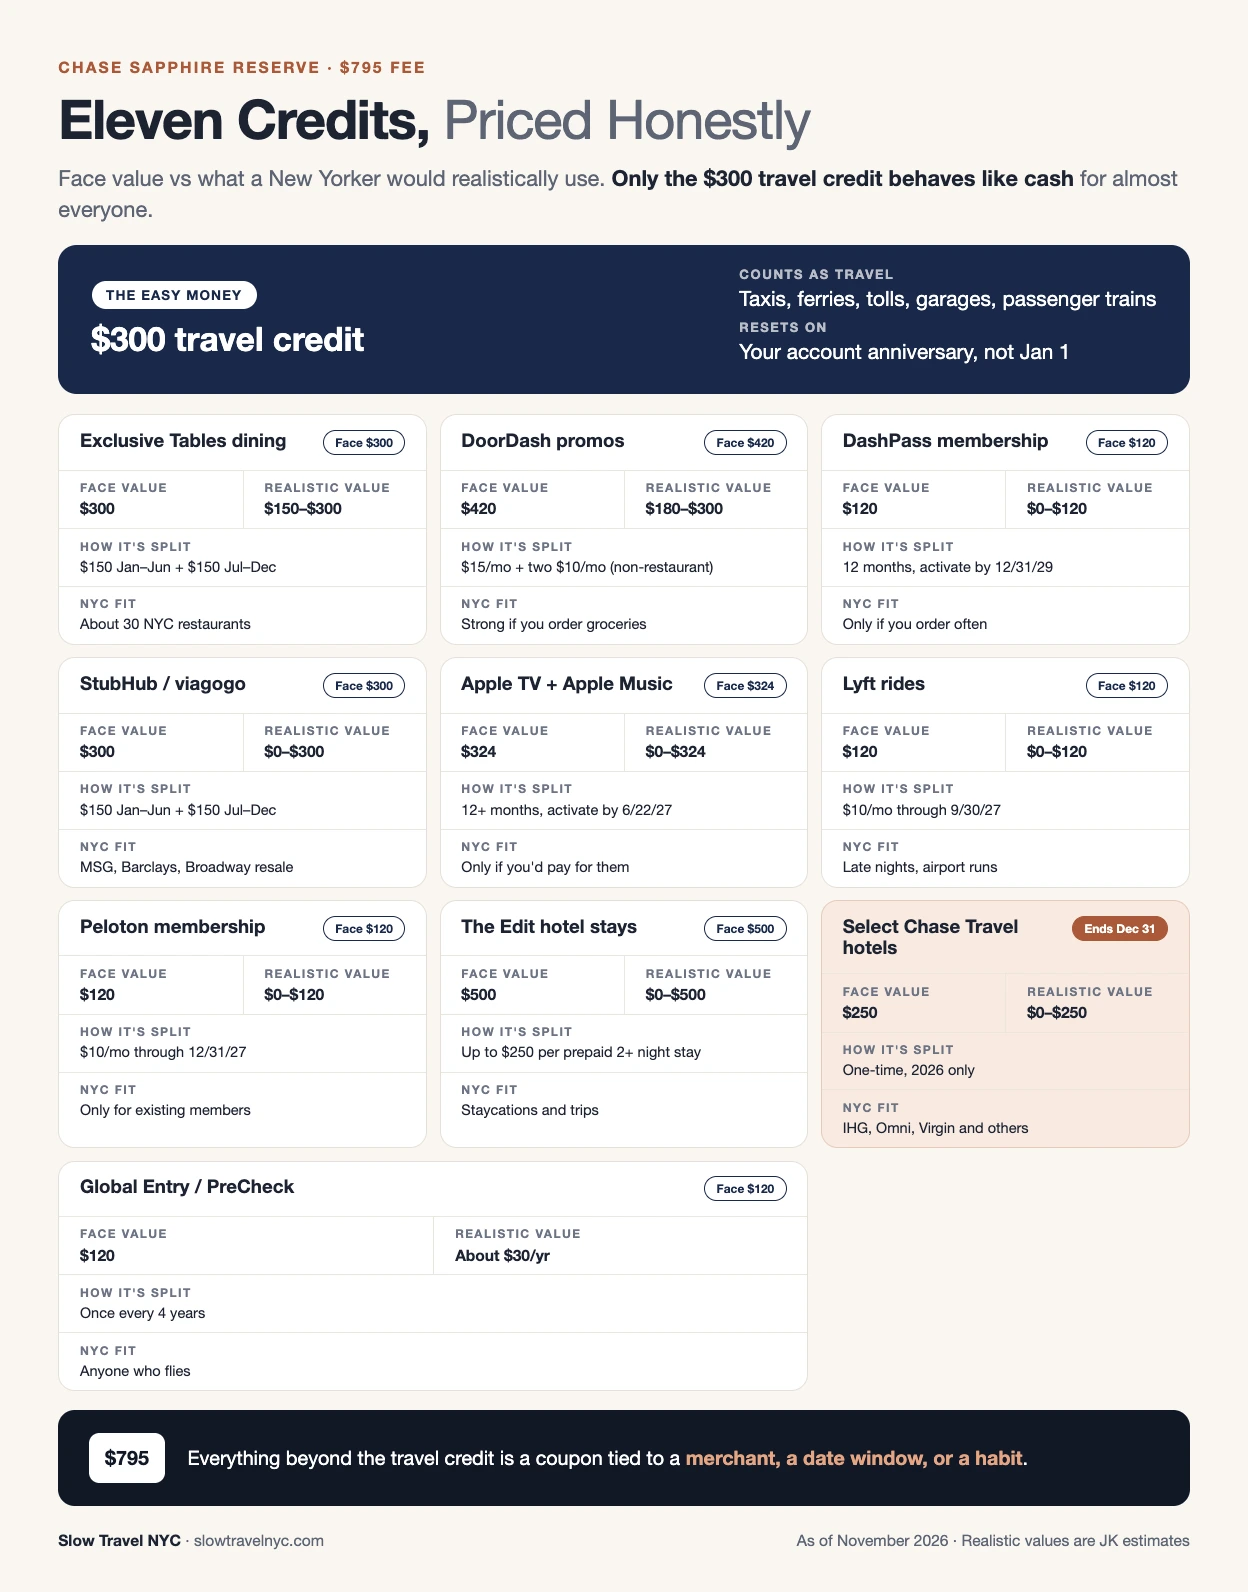
Sapphire Reserve credits in NYC, priced honestly

Infographic of Chase Sapphire Reserve credits for New Yorkers with face value, how each splits, and realistic yearly value

Laid out like this, the Sapphire Reserve credits in NYC fall into two groups. Only one credit, the $300 travel credit, behaves like cash for almost everyone. Everything else is a coupon tied to a merchant, a calendar window, or a habit.

The $300 Travel Credit Is the New Yorker’s Easiest Win

A yellow taxi driving past lit storefronts on a city street at night

Chase defines the travel category broadly. Its card terms list taxis, limousines, ferries, toll bridges and highways, parking lots and garages, buses, and passenger trains alongside airlines and hotels. For someone who lives here, that means the credit can disappear into ordinary life: a few cab rides home from dinner, a month of garage parking, E-ZPass tolls on a trip upstate, or Metro-North tickets to the Hudson Valley.

Two details matter. First, the credit resets on your account anniversary, not on January 1, so check your own renewal month. Second, purchases covered by the credit don’t earn points, which slightly reduces the value of the earning rates while the credit is being used up.

What I’d verify: Subway and bus taps through OMNY should logically fall under “passenger trains” or “buses,” but I haven’t confirmed how every OMNY charge codes. Look at your statement after a week of commuting before you count on it.

The $300 Dining Credit: Exclusive Tables Only

This is where the card gets more selective. The dining credit works only at restaurants in the Sapphire Reserve Exclusive Tables program on OpenTable, with up to $150 from January through June and another $150 from July through December. The halves do not roll over.

As of a July 2026 check, AskSebby counted 30 NYC restaurants on the list, down from a longer earlier version. The list leans toward places like Don Angie, Estela, l’abeille, and the Dining Room at Gramercy Tavern. It also includes neighborhood spots where $150 covers a meaningful share of an ordinary dinner: Joseph Leonard, Fairfax, Jeffrey’s Grocery, Scarr’s Pizza, and SAPPEISAN. Always check the live Exclusive Tables page on OpenTable before booking, because Chase says the list can change.

Candlelit restaurant bar counter with glasses and warm light reflecting on the wood

The slow-travel angle here is practical. A credit that pushes you toward a tasting menu you wouldn’t otherwise book isn’t saving money; it’s moving it. The better use is a restaurant already on your shortlist, ideally a bar seat on a weeknight when the room is calm. If you’re comparing this with Amex’s Resy-based dining perks, my Michelin restaurants and credit card perks guide covers that side.

Chase’s terms also exclude purchases made through third-party payment processors or delivery platforms. Takeout ordered through an app won’t trigger the credit; paying the restaurant directly at the table should.

DoorDash, Lyft, Apple, Peloton, and StubHub: The Habit Credits

These are the credits that look largest on paper and vary the most in real life.

DoorDash: $15 a month is easy, the $10s take planning

As of October 1, 2026, Chase lists a $15 monthly promo on any qualifying DoorDash order plus two $10 promos each month for non-restaurant orders such as groceries and household items, available through December 31, 2029. The discounts apply to the subtotal only, and any unused value on a single order is forfeited.

For a New Yorker who already orders groceries through DoorDash, this is closer to real money than it sounds. For someone who shops at the corner market and the Union Square Greenmarket, the $10 promos may go unused most months.

Lyft: useful, with a narrow definition of a ride

The $10 monthly Lyft credit applies only to rideshare modes like Standard, Extra Comfort, XL, and Black through September 30, 2027. It doesn’t cover bike or scooter rides, so Citi Bike, which Lyft operates, doesn’t count toward the credit. Chase does say eligible Lyft bike rides and memberships bought in the Lyft app earn 5x points through the same date, which may help if you’re a Citi Bike member, but check how your membership is billed.

Apple, Peloton, and StubHub: value only what you’d buy anyway

Chase values the Apple TV and Apple Music subscriptions at $324 a year. If you already pay for both, that’s close to real savings. If you don’t, the honest value is zero. The same rule applies to the $10 monthly Peloton credit and the StubHub credit, which offers $150 in each half of the year through 2027. A Knicks game or a resale Broadway seat you were already planning to buy is a good use. A ticket bought because the credit was expiring is a purchase, not a savings.

Hotel Credits for Staycations

Bedside wall lamp glowing beside a hotel bed with white pillows

The Edit credit gives up to $250 back on each prepaid stay of two nights or more booked through Chase’s The Edit collection, up to $500 per calendar year. The Edit stays also come with perks Chase lists as a $100 property credit, daily breakfast for two, and room upgrades and early check-in when available.

For residents, the question is whether you’d ever book two nights in a hotel in your own city or a nearby escape. Some New Yorkers do, especially for a birthday, a parent visit, or a quiet weekend away from a loud apartment. Prepaid rates through a portal can run higher than booking direct, so compare the real total, including NYC hotel taxes, before treating the credit as a discount. My Amex Fine Hotels + Resorts guide uses the same approach for The Plaza and The Carlyle.

One 2026-only extra: Cardholders also get a one-time $250 credit on prepaid stays of at least two nights at select brands booked through Chase Travel in 2026, including IHG, Montage, Pendry, Omni, Virgin Hotels, Minor, and Pan Pacific, per AwardWallet’s guide to the credit. In New York, that could mean a Kimpton or InterContinental property, Omni Berkshire Place, or Virgin Hotels New York City. Look for the eligibility label in Chase Travel. It ends December 31, 2026.

Chase Sapphire Reserve for NYC Residents: Three Profiles

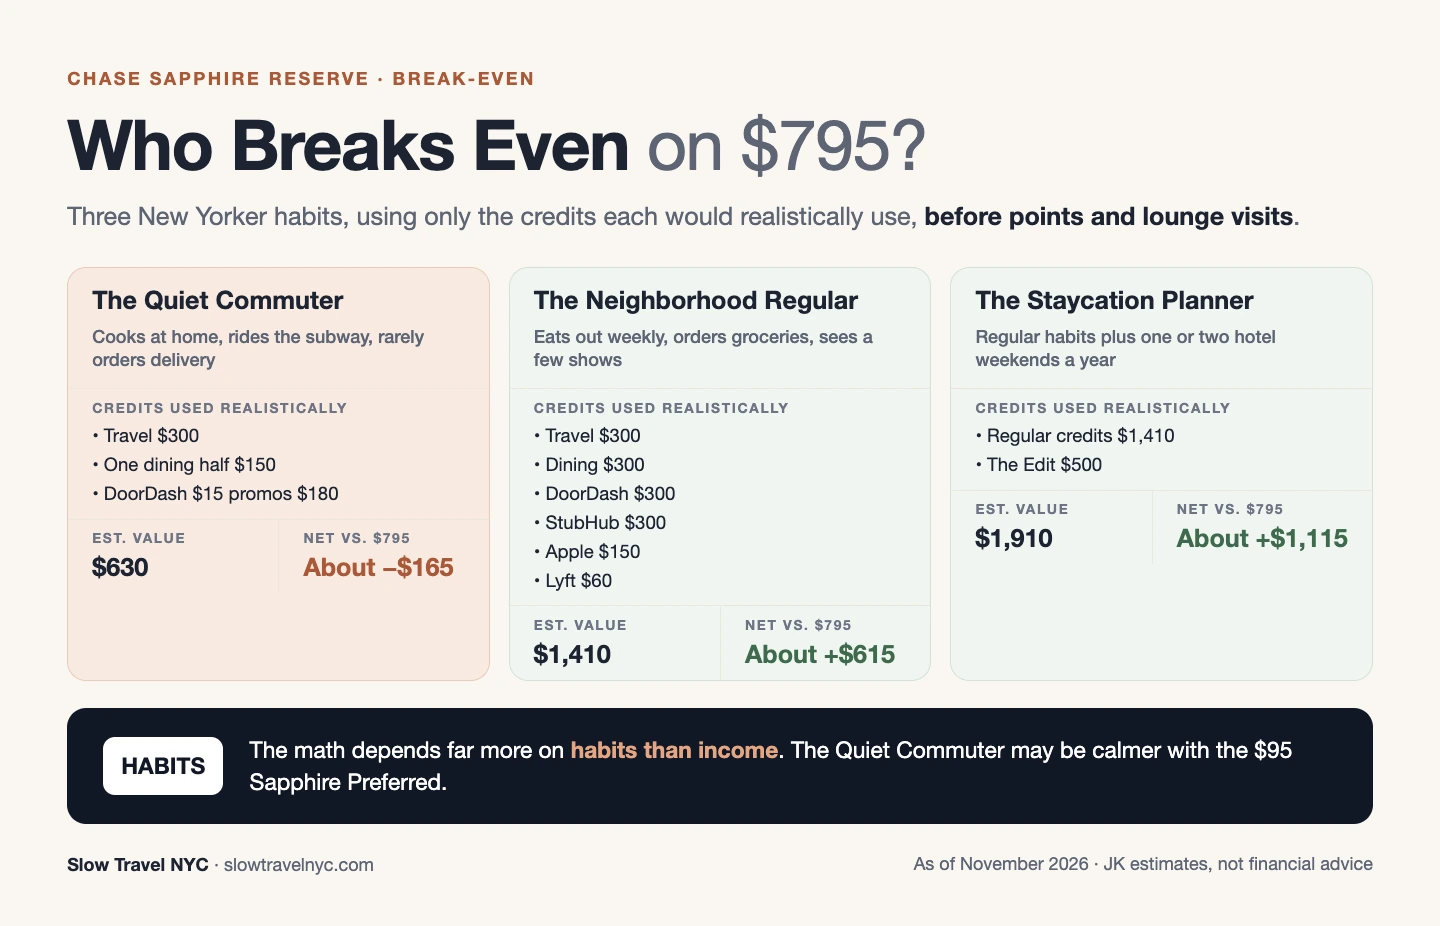
The math depends far more on habits than on income. These are my estimates, using only the credits each profile would realistically use, before points and lounge visits.

Infographic comparing three New Yorker profiles and whether Chase Sapphire Reserve credits cover the $795 annual fee

The Quiet Commuter is the most “slow” New Yorker on this list, and the card works least well for that life. That isn’t a flaw in the person. It’s a reminder that premium cards reward a specific pattern of spending, and the pattern isn’t always yours.

If you want to see how these credits change the cost of an actual trip, plug the numbers into the NYC Trip Budget Calculator, and use the NYC Tip & Tax Calculator when you’re estimating restaurant checks against the $150 dining halves.

Reality Check: The Limits for New Yorkers

Open dated planner on a desk beside a laptop and a computer mouse
  • It’s a calendar job. Two semiannual credits, two monthly DoorDash promos, one monthly Lyft credit, and one anniversary-year credit all reset on different schedules. If you don’t enjoy tracking them, the value shrinks fast.
  • New York residents get slightly weaker coverage. Chase’s card terms say that for New York residents, auto rental coverage inside the U.S. is secondary to personal auto insurance, purchase protection lasts 90 days instead of 120, and lost luggage reimbursement is capped at $2,000 per bag and $10,000 per trip.
  • The restaurant list moves. About 35 NYC and nearby restaurants dropped off the Exclusive Tables list between versions, according to AskSebby’s July 2026 comparison.
  • Points earning is ordinary off-travel. Groceries, rent, and most everyday spending earn 1x. If your goal is rent rewards, see my Manhattan rent rewards and Bilt guide.
  • Authorized users are no longer cheap. At $195 each, adding a partner only makes sense if they’ll use the lounge access and their own spending.

What to Do Before December 31, 2026

If you already carry the card, November and December are when the 2026 credits either get used or disappear.

  1. Book one Exclusive Tables dinner to use the July–December $150 dining credit.
  2. Use the second StubHub half on an event you were already planning to attend, such as a holiday show or a winter game.
  3. Check the $250 select-hotel credit. If a two-night stay at an eligible brand is already in your plans, book it through Chase Travel before year-end.
  4. Claim this month’s DoorDash and Lyft credits, since monthly promos never carry over.
  5. Note your renewal month. If your annual fee posts soon, decide now whether the coming year matches the Neighborhood Regular profile or the Quiet Commuter one.

For winter flights, the card’s trip delay coverage applies after six hours or an overnight delay, up to $500 per traveler. My NYC trip delay insurance guide explains how to file if a snowstorm grounds you.

Frequently Asked Questions

Does the Sapphire Reserve travel credit work on NYC taxis and the subway?

Chase’s travel category includes taxis, buses, passenger trains, ferries, tolls, and parking garages, so yellow cabs and Metro-North tickets should qualify. Subway and bus taps through OMNY likely fall under that definition too, but check your statement to confirm how they code before relying on it.

Can I use the $300 dining credit on DoorDash or takeout?

No. The dining credit applies only to purchases made directly with restaurants in the Sapphire Reserve Exclusive Tables program on OpenTable. Chase’s terms exclude orders through delivery platforms and third-party payment processors.

Is the Chase Sapphire Reserve worth it for NYC residents who rarely fly?

It can be, but only if you’d naturally use the travel credit, both dining halves, and most of the DoorDash promos. Without those three, the remaining credits depend on subscriptions and habits that many New Yorkers don’t have.

What happens to unused Sapphire Reserve credits?

They expire. The dining and StubHub credits reset every six months, the DoorDash and Lyft credits reset monthly, and the travel credit resets on your account anniversary. None of them roll over.

Should I downgrade to the Sapphire Preferred instead?

If the credits don’t fit your life, the Sapphire Preferred has a $95 annual fee as of November 2026 and keeps you in Chase’s points ecosystem. You’d give up the Reserve’s credits, lounge access, and higher earning on Chase Travel. Call Chase before your renewal to ask about product change options.

The Slow Answer

The Sapphire Reserve isn’t really a luxury card for New Yorkers. It’s a set of small, scheduled rebates on things city people already do: take a cab, order groceries, book dinner, buy a ticket. If those things are already part of your week, the $795 fee can disappear quietly.

If they aren’t, the card asks you to change your routine to justify it, and that’s the opposite of slow living. Price each credit at what you’d spend anyway, and the right answer usually becomes obvious within a few minutes.

Related Reading

Best Hotel Points for NYC: Hyatt vs Marriott vs Hilton (2026)

The best hotel points for NYC are not the ones with the biggest numbers. Here is how Hyatt, Marriott and Hilton actually price a Manhattan night in 2026, and how to tell when a points stay beats paying cash.

A hotel room with golden sunset light glowing through sheer curtains and a view of the sky

Disclosure: This post may contain affiliate links. Loyalty program rules, award prices and card terms change often, and nothing here is financial advice. Check the program’s own site before you transfer or redeem. See our full disclosure policy.

This spring, one reviewer booked a night at the Conrad New York Midtown. It cost either $641 including tax or 95,000 Hilton Honors points. A few blocks away, The Time New York now starts at 15,000 World of Hyatt points after dropping a category in May. Both rooms are in Midtown. The point totals differ by more than six times.

That gap explains most of what you need to know about the best hotel points for NYC. A bigger point balance does not mean more nights. What decides it is how each program prices a Manhattan night, what fees still show up at checkout, and whether your credit card points can move there at all. Every figure below is as of October 2026.

Key Takeaways

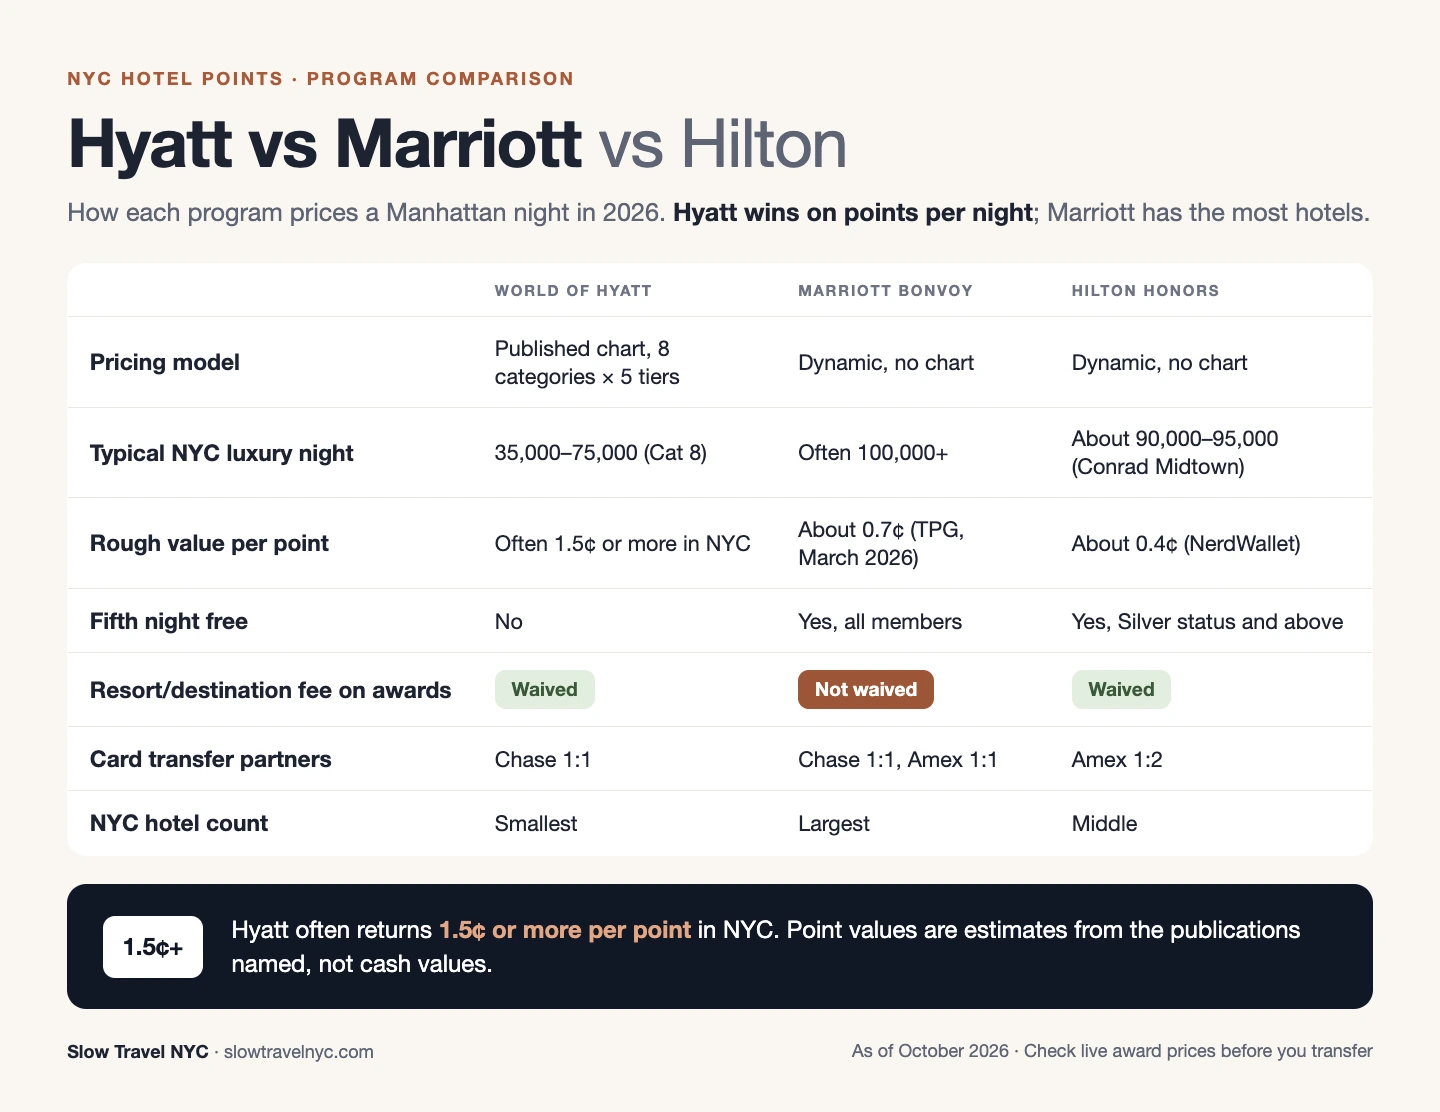
  • World of Hyatt usually gives the most value per point in NYC. It still has a published chart: Category 5 hotels cost 15,000 to 35,000 points a night, and Category 8 costs 35,000 to 75,000.
  • Marriott Bonvoy has the most hotels in NYC, but prices are fully dynamic. Luxury nights often cost 100,000 points or more, and resort or destination fees are not waived on award stays.
  • Hilton Honors uses big numbers for small points. A flagship Conrad night near 95,000 points can still be a decent Hilton redemption, because a Hilton point is worth less than a Hyatt point.
  • Transfers decide a lot. Chase points go to Hyatt 1:1. Amex points go to Hilton 1:2 and to Marriott 1:1. Transfers are final.
  • Check the cents-per-point math before every booking. The same hotel can be a great deal on a Tuesday in February and a poor one during Thanksgiving week.

How Hyatt, Marriott and Hilton Price a Night in New York

All three programs will let you sleep in Manhattan on points. They count very differently, and New York, with some of the highest cash rates in the country, makes those differences larger.

A silver laptop on a wooden table with a small candle holder and a phone beside it

World of Hyatt: still a chart, now with five tiers

On May 20, 2026, Hyatt replaced its three pricing levels (Off-Peak, Standard, Peak) with five: Lowest, Low, Moderate, Upper and Top. Each category still has a fixed floor and ceiling, which no other big chain offers. The current Hyatt award chart puts a Category 5 standard room at 15,000 to 35,000 points a night, a Category 6 at 20,000 to 40,000, a Category 7 at 25,000 to 55,000 and a Category 8 at 35,000 to 75,000.

The same update moved several New York hotels. Andaz 5th Avenue went from Category 7 to 8, The Beekman went from 6 to 7, and The Time New York dropped from 6 to 5. Upgraded Points noted that The Time can now cost as little as 15,000 points a night.

Marriott Bonvoy: the biggest footprint, no chart

Marriott has more New York hotels than either rival, from Moxy and AC to The St. Regis and two Ritz-Carltons. It publishes no award chart, so each night is priced by demand. In July 2026, The Points Guy reported top nightly rates at The Ritz-Carlton New York, NoMad of 160,000 points, up from 142,000 a year earlier.

Marriott does have one structural advantage: every member gets the fifth night free on award stays, with no status required.

Hilton Honors: big numbers, small points

Hilton also prices dynamically, and its numbers look alarming at first. The Conrad New York Midtown, an all-suite hotel near Central Park, usually prices standard rewards at about 90,000 to 95,000 points. But a Hilton point is worth far less than a Hyatt point. NerdWallet values Hilton points at 0.4 cent, so 95,000 points is less of a splurge than it sounds.

Comparison chart of Hyatt, Marriott and Hilton point pricing, fees and transfer partners for NYC hotels

As of October 2026. Point values are estimates from the publications named, not cash values.

Hyatt vs Marriott vs Hilton NYC: Real Hotel Examples

Program-level comparisons only go so far. You book a specific hotel on a specific date. These are reported price ranges for well-known New York properties. Live prices on your dates will differ.

A long carpeted hotel corridor with wall sconces and doors on both sides
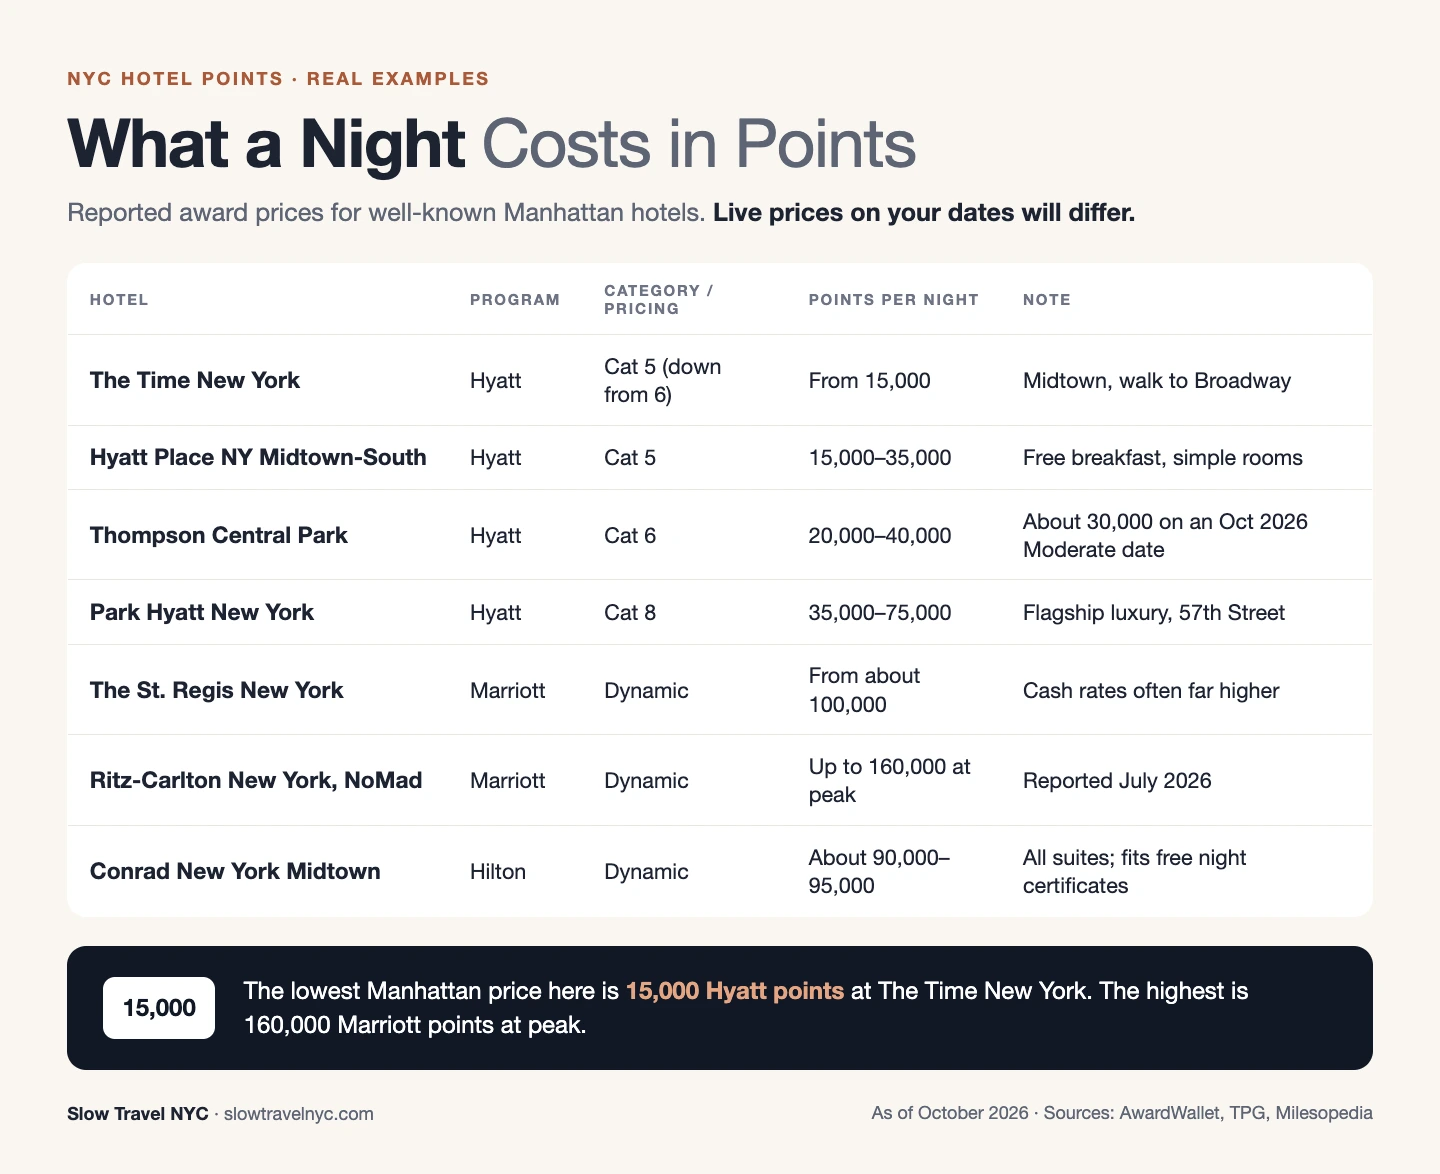
Hotel-by-hotel chart of reported award prices at Hyatt, Marriott and Hilton properties in Manhattan

As of October 2026. Sources: AwardWallet (Thompson), TPG (St. Regis), Milesopedia (Conrad). Always check live availability before transferring points.

Thompson Central Park is a useful reference point. AwardWallet found an October 2026 night priced at 30,000 points, up just 1,000 from the old chart. For a Category 6 near the park, that was a smaller increase than many feared. If you run Central Park loops on your trips, our guide to boutique hotels near Central Park with a gym covers what is nearby on a paid rate.

The Math: When a Points Night Is Worth It

There is one formula, and it is simple:

Cash rate after taxes and fees ÷ points required = cents per point (¢).

Compare the result with a reasonable value for that program. If you get less, pay cash and keep the points for a better night.

A hand holding a smartphone showing a calculator app over a paper folder

A real Hilton example. The Conrad night above: $641 ÷ 95,000 points = about 0.67¢ per point. That is well above NerdWallet’s 0.4¢ baseline for Hilton, so it was a sound use of Hilton points, even though 95,000 sounds like a lot.

An illustrative Hyatt example. Suppose a Category 6 night prices at 25,000 points when the cash rate is $450 after tax. $450 ÷ 25,000 = 1.8¢. That is a strong result. If the same night jumped to the 40,000-point Top tier, the value would fall to about 1.1¢, and you should probably reconsider.

An illustrative Marriott example. A 100,000-point night at a hotel charging $900 works out to 0.9¢, only modestly above TPG’s 0.7¢ estimate. Marriott redemptions in Manhattan often land here: acceptable, but rarely remarkable.

Hotel taxes matter in this calculation. Cash nights in New York carry sales and occupancy tax plus fixed per-night fees. Include them when you calculate the cash rate, because that is the money a points night saves you. Our NYC Trip Budget Calculator can help you price the cash version of the trip first.

Where Your Credit Card Points Should Go

For most New Yorkers, the hotel points they care about come from a credit card, not from paid stays. The transfer partners decide which program makes sense for you.

A brown leather card wallet holding several credit cards
Card currencyHyattMarriottHiltonBest NYC use
Chase Ultimate Rewards1:11:1NoHyatt, almost always
Amex Membership RewardsNo1:11:2Hilton during transfer bonuses; Marriott rarely

As of October 2026. Chase and Amex both say travel partner transfers are final.

If you hold a Chase Sapphire card, Hyatt is usually the obvious choice. Amex points have no Hyatt option. Their Hilton ratio doubles the point count, though Hilton points are worth roughly half as much each. That trade improves during Amex’s occasional transfer bonuses to Hilton. If you also use those Amex points for flights, our guide to business class to NYC with points explains why airline transfers usually earn more.

The most important rule applies to every program: find the award night first, then transfer. A transfer cannot be reversed, and Hyatt’s new tiers mean the price you saw in September may not be the price you see now.

Fees, Taxes and the Fifth Night

The headline points price is not the full cost. Two rules quietly shift the comparison between programs.

A hotel lobby with a marble reception counter and large windows

Resort and destination fees. Plenty of New York hotels charge a daily “destination fee” for Wi-Fi, a gym or a drink voucher. Hilton and Hyatt waive these on stays booked entirely with points, but Marriott does not. On a five-night Marriott award with a $40 nightly fee, you would still owe about $200 in cash, plus any tax on the fee. Hyatt goes further: TPG reports no taxes or fees on its award redemptions.

The fifth night free. Marriott gives every member a free fifth night when you book five consecutive award nights, and the free night is the cheapest of the five, not necessarily the fifth. Hilton offers the same benefit to Silver status and above, which you can get with Hilton’s no-annual-fee Amex card. Hyatt has no equivalent. For a week-long stay, this can narrow the gap between Marriott or Hilton and Hyatt.

Even on a points stay, you will probably still tip housekeeping and the bell desk. Our NYC Tip & Tax Calculator covers the usual amounts.

Which Program Fits Which Kind of NYC Trip

The best program depends on how you travel, not on a ranking.

An armchair and a round table with a lamp and a cup beside a curtained window
  • Solo or couple, three nights, flexible dates: Hyatt. A Category 5 or 6 night in Midtown at Low or Moderate pricing is often the best use of points in the city.
  • Five nights or more: Run the numbers on Marriott and Hilton. The fifth night free can make a longer stay competitive, especially at a mid-range hotel.
  • Once-a-year splurge: A Hilton Aspire free night certificate at the Conrad Midtown, or a Hyatt Category 8 night on a quiet date. Avoid peak holiday weeks, when Top-tier pricing applies.
  • Downtown or Brooklyn base: Marriott, simply because it has the most hotels outside Midtown.
  • Already have status: Elite benefits like breakfast and late checkout can matter more than points prices. Hyatt Globalist and Hilton Gold breakfast benefits add real value in a city where breakfast for two can top $60.

Reality Check

Points can still be worth using, but New York is one of the hardest places to get good value from them.

  • Award availability is uneven. “No blackout dates” does not mean a standard room is open every night. Busy weeks like the Marathon, Thanksgiving, December and fashion week sell out early.
  • Hyatt’s new top tiers bite at the worst times. Hyatt says it will limit Upper and Top pricing in 2026 but expand it later. Expect your favorite dates to cost more over time.
  • Marriott raises prices without notice. With no chart, a hotel can cost 20% more points next year and nothing is announced.
  • Small hotel rooms are still small. A 15,000-point Hyatt Place room is a good deal, but it is not a suite. Know what you are booking.
  • Free night certificates have rules of their own. Category caps, expiration dates and standard-room limits all apply. We’ll cover NYC certificates separately.

A Calmer Way to Use Points in New York

Here’s my bias as a slow traveler: the best points night is often not the most expensive room you can book. It is the one that buys you time. That might mean a later checkout so you are not dragging a suitcase through Midtown at 11 a.m., or a hotel close enough to the park that a morning walk takes ten minutes instead of a subway ride.

An empty park bench along a path under autumn trees

A modest Category 5 night near Bryant Park or the park’s southern edge, with the points saved for a second trip, is often worth more than one Top-tier night spent mostly in transit. Book where you want to start your mornings, then let the city slow down. Our list of the quietest places to sit in Midtown is a good companion to any Midtown points stay.

FAQ

What are the best hotel points for NYC in 2026?

For most travelers, World of Hyatt. Its published chart keeps many Manhattan hotels between 15,000 and 40,000 points a night, and it waives resort fees on award stays. Marriott has the most hotels and Hilton works well with free night certificates, but both often require far more points for similar rooms.

Is it worth transferring Chase points to Hyatt for New York?

Usually yes, if you have found an available award night first and the math reaches about 1.5¢ per point or better. Chase transfers to Hyatt at 1:1, but transfers cannot be reversed, so confirm the date and price before you move any points.

Hyatt vs Marriott vs Hilton in NYC: which is best for a long stay?

For five nights or more, compare all three. Marriott gives every member the fifth night free, and Hilton does the same for Silver members and above. Hyatt has no fifth-night benefit, but its lower nightly prices often win anyway. Run the total points and any remaining fees for your exact dates.

Do you pay hotel tax on a points stay in New York?

It depends on the program. TPG reports that Hyatt award redemptions carry no taxes or fees. With other programs, check your folio, because Marriott can still charge destination fees on award nights. On cash nights, New York adds sales and occupancy tax plus per-night fees.

Final Thoughts

The best hotel points for NYC come down to a calm, repeatable habit, not a single winner. Check the live award price, divide the cash rate by the points, and compare the result with what that program’s points are usually worth. Hyatt will usually come out ahead in Manhattan. Marriott and Hilton earn their place on long stays, in other neighborhoods, and when you have a certificate to use.

If the math does not work, pay cash and save the points for a quieter week. New York will still be here, and it is easier to enjoy when you are not watching the meter.

Related Reading

Business Class to NYC With Points: 2026 Transfer Partners for Beginners

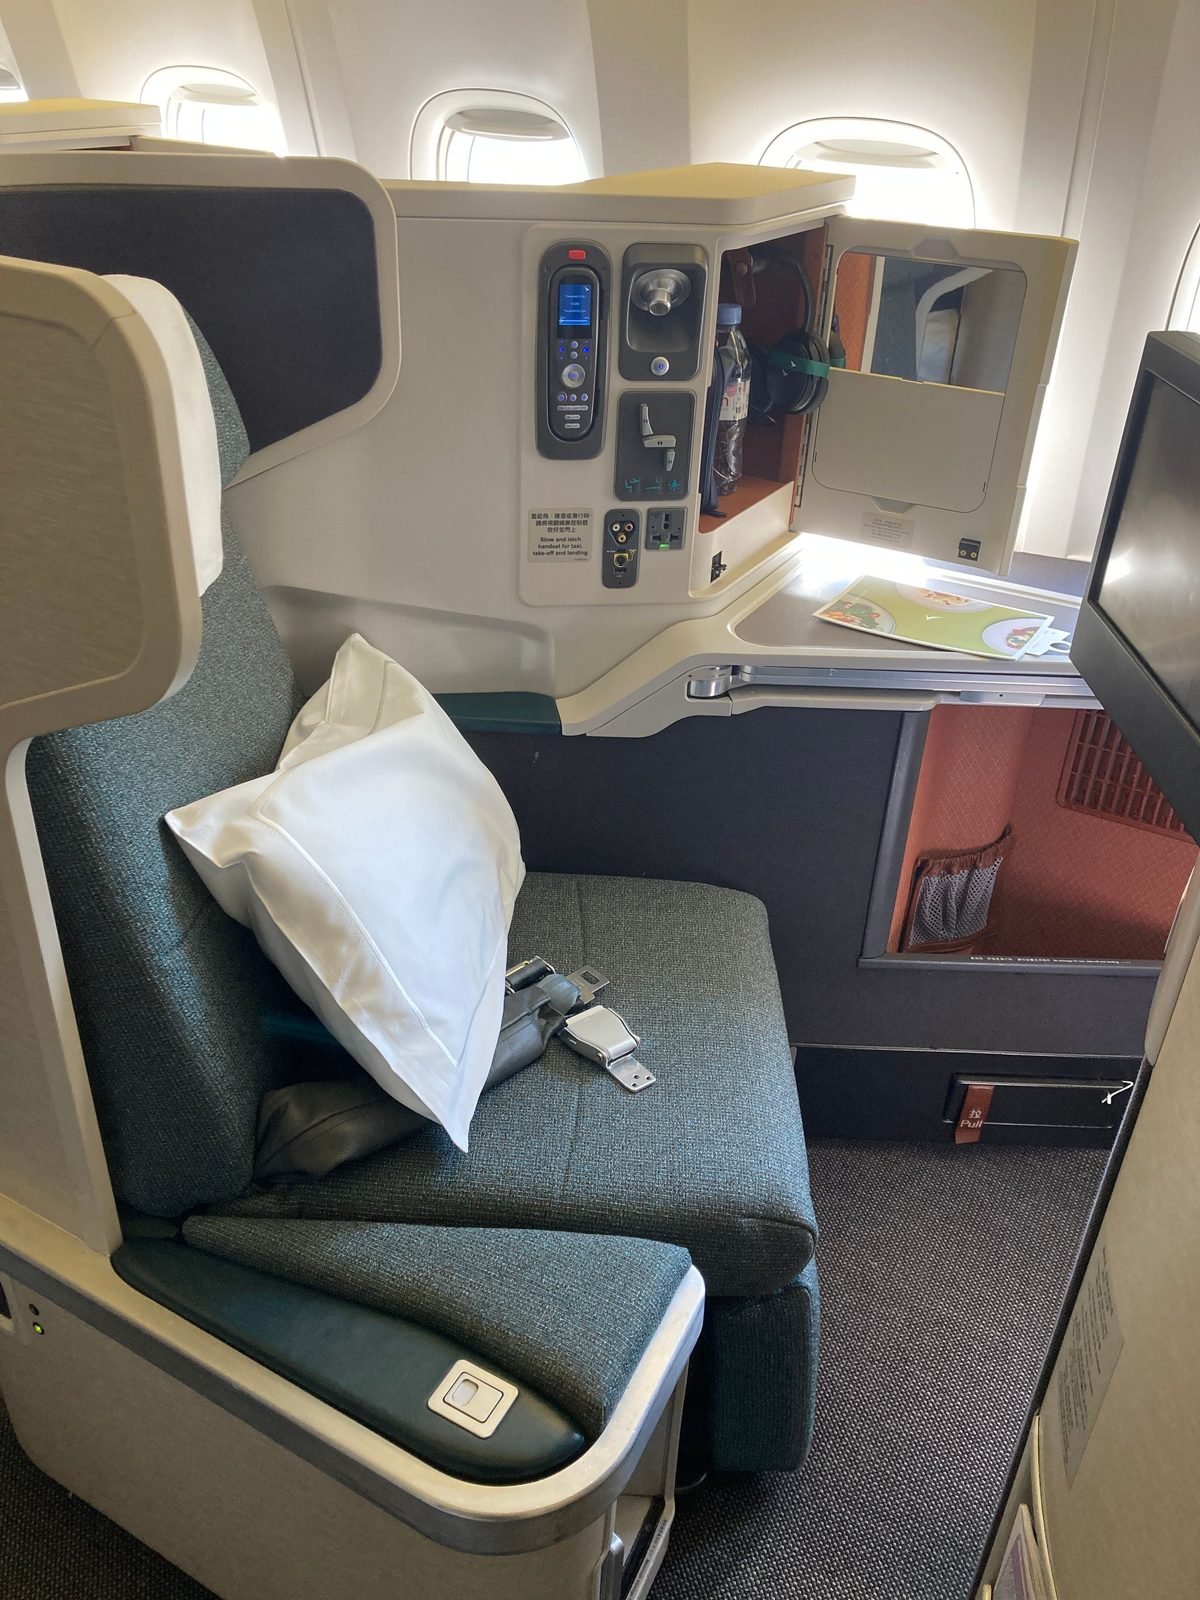
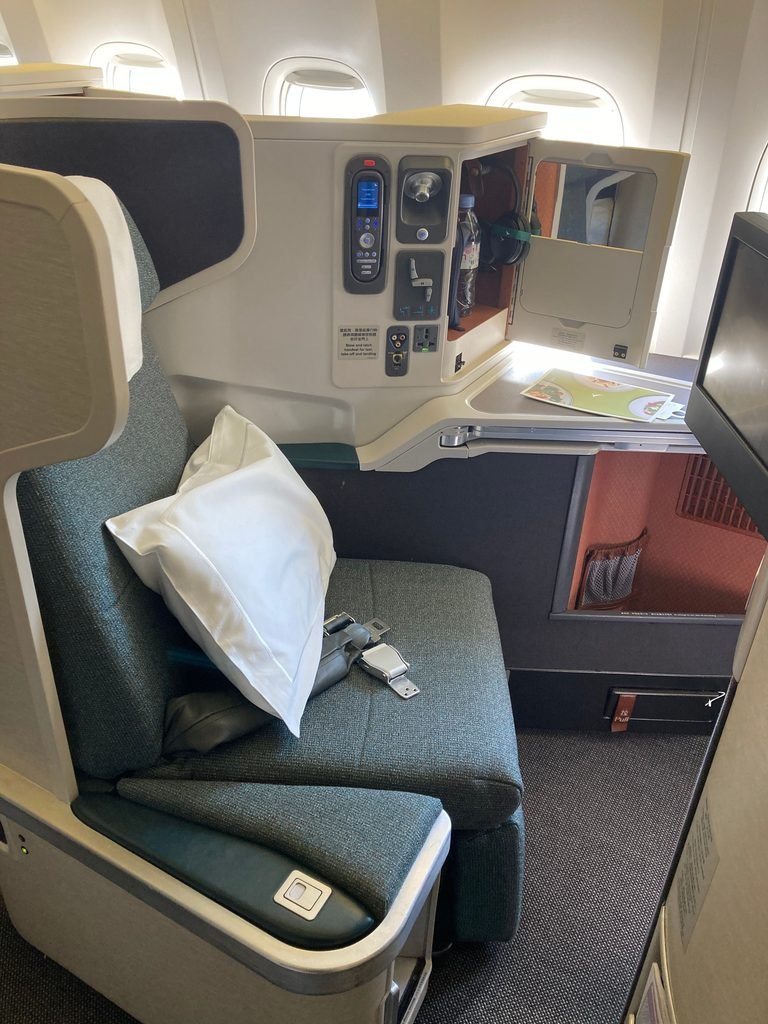
Lie-flat seat in business class to NYC with points on a transatlantic flight

Cash fares for lie-flat seats across the Atlantic routinely run well over $1,500 each way, and they climb much higher at peak times. Yet plenty of ordinary travelers fly business class to NYC with points for a fraction of that, paying mostly taxes and fees. The trick is not a secret credit card. It is knowing how to move your points to the right airline program.

If you have ever wondered how transfer partners for beginners actually work, this guide walks you through it using current 2026 prices, not the outdated numbers still floating around the internet. You will see three real sweet spots, the hidden fees that catch newcomers, and a step-by-step booking order that protects your points.

Prices below were checked on October 2, 2026. Award charts change often, so always confirm on the airline’s site before you transfer anything.

Manhattan skyline at dusk, the destination for award flights from Europe

Quick Answer

  • The best-value way to book business class to NYC with points in 2026 is usually Iberia Avios (from Madrid) or Air Canada Aeroplan (on Star Alliance partners).
  • Transfers from Chase, Amex and Capital One are one-way and mostly 1:1, so confirm seats first.
  • The famous “$5.60” figure is a real US security fee, but it only applies to certain US-departing awards and says nothing about the fees on the way back.

Why Transfers Beat the Card Portal for Business Class to NYC With Points

Passport, laptop and credit cards laid out for planning an award flight

Most cardholders redeem points inside the bank’s travel portal, where each point is worth a fixed amount, roughly 1 to 1.5 cents. At that rate, a $1,500 business fare costs 100,000 to 150,000 points.

Transfer partners work differently. You move points into an airline’s loyalty program, usually at a 1:1 ratio, and pay the airline’s award price instead of a cash-based price. Here is a simple, hypothetical example:

  • Cash fare: $1,500 one-way
  • Award price: 40,500 points + about $125 in taxes
  • Value per point: ($1,500 − $125) ÷ 40,500 ≈ 3.4 cents

That is more than double the typical portal value, and the gap gets bigger when cash fares spike.

Transfer Partners for Beginners: How the Points Actually Move

Three bank programs dominate the beginner scene:

  • Chase Ultimate Rewards transfers 1:1 to Aeroplan, British Airways, Iberia and Virgin Atlantic, and the transfers are usually instant.
  • American Express Membership Rewards also reaches those four programs at 1:1, though Iberia transfers can take a day or two.
  • Capital One Miles reaches British Airways and Virgin Atlantic at 1:1. It does not list Iberia directly, but you can move Avios between your British Airways and Iberia accounts. Check the ratio for Aeroplan before you move anything.

Partner lists change. Amex, for example, dropped Qantas and Etihad as transfer partners in mid-2026 (AwardWallet on Etihad). Check your issuer’s current list, and compare it against The Points Guy’s transfer partner guide.

3 Sweet Spots for Business Class to NYC With Points in 2026

Route / CabinPartnerPoints (one-way)Typical fees
Madrid ↔ New York, BusinessIberia Plus (Avios)40,500 off-peak / 59,000 peakroughly $125 from the US
East Coast ↔ Western Europe, BusinessAir Canada Aeroplanfrom about 60,000taxes + CA$39 booking fee, no fuel surcharges
US ↔ Europe, Delta OneVirgin Atlantic47,500–57,500+over $1,000 each way in reported surcharges

1. Iberia Avios: Still a Strong Pick, Just Pricier

Madrid cityscape, gateway for Iberia Avios business class awards to New York

For years, Iberia’s 34,000-Avios business award was the star of the points world. Iberia introduced a new award chart that raised off-peak East Coast-to-Spain business to 40,500 Avios and peak dates to 59,000 (AwardWallet). British Airways charges the same Avios rates, but Iberia’s cash fees are lower, so book through Iberia.

Even after the increase, this is a good deal compared with dynamic-pricing programs. The catch is availability: bookable business seats are far scarcer than the published prices suggest, so search flexible dates.

2. Air Canada Aeroplan: Star Alliance Business Class Without Fuel Surcharges

Aeroplan lets you book Lufthansa, Swiss, Austrian and other Star Alliance partners, and it does not pass on fuel surcharges. Business class from the US East Coast to Western Europe has been priced from about 60,000 points, plus taxes and a CA$39 partner booking fee (Points Path). Aeroplan also lets you add a stopover on most one-way awards for 5,000 points.

Aeroplan raised prices on non-Air Canada partners as of June 1, 2026, with first class hit hardest (Milesopedia). It also uses dynamic pricing on some partner flights (AwardWallet), so treat “from 60,000” as a starting point. Search at Aeroplan.com before you transfer.

3. Virgin Atlantic: Delta One Looks Great Until You Check the Fees

Airport departures board while checking Delta One award fees on Virgin Atlantic

Booking Delta One through Virgin Atlantic used to be a legendary trick. Virgin later added a large carrier surcharge that pushed total fees above $1,000 per person each way, and seats are very hard to find (The Points Guy). Delta One via Virgin Atlantic is therefore a “check, but don’t count on it” option. Delta economy awards on Virgin do not carry that surcharge, and Air France-KLM Flying Blue can price the same Delta flights with lower fees.

The Truth About the “$5.60” Fare and First Class

The $5.60 number is the US September 11 security fee, which applies to flights departing the United States. Flights into New York usually add other government and airport charges, and some carriers add surcharges on top. Plan on $5.60 to $150 or more per segment depending on the airline and direction, not a flat nickel-and-dime amount.

First class to New York on points exists, but it is rare and expensive. Lufthansa First through Aeroplan, for example, prices far above business. If you are new to this, treat business class as the realistic goal and first class as a bonus if it shows up.

Step-by-Step: Booking Business Class to NYC With Points

Follow this order every time you book business class to NYC with points:

  1. Search first. Create free accounts with Iberia, Aeroplan and Virgin Atlantic, and look for award seats on your dates before touching your bank account.
  2. Check the total cost. Compare the points price and the cash fees, in both directions.
  3. Link your accounts. Add your airline loyalty number in your Chase, Amex or Capital One dashboard.
  4. Transfer only what you need. Transfers cannot be reversed. If seats vanish after you transfer, the points stay with the airline.
  5. Book right away. Refresh the airline site, confirm the miles have arrived, and complete the reservation.

Transfer Partners for Beginners: Mistakes to Avoid

  • Transferring speculatively. Never move points “just in case.” Confirm live availability first.
  • Ignoring transfer bonuses. Issuers regularly run 20% to 30% bonuses. Chase, for instance, ran a 20% bonus to British Airways, Iberia and Aer Lingus in March 2026. With a 30% bonus, a 40,500-Avios award costs about 31,150 bank points. Track live offers at NerdWallet or The Points Guy.
  • Chasing stale charts. Many blog posts still quote pre-devaluation prices. Always check the airline’s own search results.
  • Forgetting fees. A cheap points price with $1,000 in surcharges is not a bargain.

Which Card Should You Start With?

Beginners usually start with a mid-fee card that earns transferable points, then add a premium card later if the travel credits and lounges make sense. Welcome bonuses change often and vary a lot by offer, so compare the current offer on the issuer’s website rather than relying on a number you saw months ago. Also remember that most welcome bonuses require meeting a minimum spend in the first few months, so only apply if you can do that comfortably.

FAQ

Can I really fly business class to NYC with points for under $100?

Sometimes, on certain US-departing routes with no surcharges. For flights into New York, plan on more in taxes and fees. Iberia and Aeroplan are the most reliable for low fees.

Are transfer partners for beginners worth it if I only fly once a year?

Usually yes, if you can get a good welcome bonus and book a premium cabin. One well-timed redemption can be worth several thousand dollars in cash fares.

Do credit card points expire after I transfer them?

Airline miles have their own expiration rules, so read the program terms. In many programs, any account activity keeps miles alive.

Final Verdict

Booking business class to NYC with points is still one of the best uses of credit card rewards in 2026, but the easy 34,000-Avios and $5.60 stories are out of date. Start with Iberia and Aeroplan, check fees before you transfer, and use this guide to learn transfer partners for beginners the safe way: search first, transfer second, book immediately.

Disclosure: This post is for information only and is not financial advice. Some links may be affiliate links. Award prices, fees and partner lists change often, so verify them on the airline’s and issuer’s websites before you act.

Related posts you might enjoy: