Disclosure: Card terms change often, and this is not financial advice. Figures are as of November 2026 and come from Chase’s public card page unless noted. Some links on this site may be affiliate links; see our disclosure policy.
Seven hundred ninety-five dollars works out to about $66 a month, or roughly 22 subway rides at the $3 base fare. It is also the annual fee on the Chase Sapphire Reserve, and that number is why so many people are now asking whether the Chase Sapphire Reserve for NYC residents still makes sense once the welcome bonus is spent.
Most reviews answer that question from an airport. This one stays in the city. The lounges are real, but if you live here, the question is whether the Sapphire Reserve credits in NYC fit the way you already eat, move, and spend your evenings in New York. I’ve written separately about NYC airport lounge credit cards, so lounges get one paragraph here and the rest of the page goes to the credits you’d use at home.
Quick Answer
- The fee: $795 a year, plus $195 per authorized user (as of November 2026).
- The easy money: The $300 travel credit is the most flexible piece for a New Yorker. Chase’s travel category includes taxis, ferries, tolls, parking garages, and passenger trains.
- The conditional money: The $300 dining credit only works at roughly 30 NYC restaurants on Chase’s Exclusive Tables list, split into two $150 halves.
- The habit money: DoorDash, Lyft, Peloton, StubHub, and Apple credits only count if you’d pay for those services anyway.
- The verdict: If you’d naturally use the travel credit, both dining halves, and most of the DoorDash promos, you’re close to break-even before lounges. If not, the $95 Sapphire Preferred is the calmer choice.
- Deadline: The July–December dining and StubHub halves, and the 2026-only $250 hotel credit, all expire December 31, 2026.
What the $795 Actually Buys (As of November 2026)
Chase markets the card as delivering “$3,000+ in annual value.” That figure assumes you use nearly every credit, every month, at full face value. The useful exercise is to price each credit at what it would replace in your own budget, not at the number on the brochure.
The card earns 8x points on Chase Travel purchases, 4x on flights and hotels booked direct, 3x on dining worldwide, and 1x on everything else, according to the Chase Sapphire Reserve card page. Points are part of the story, but for a resident who mostly spends locally, the statement credits do the heavy lifting.
Sapphire Reserve credits in NYC, priced honestly
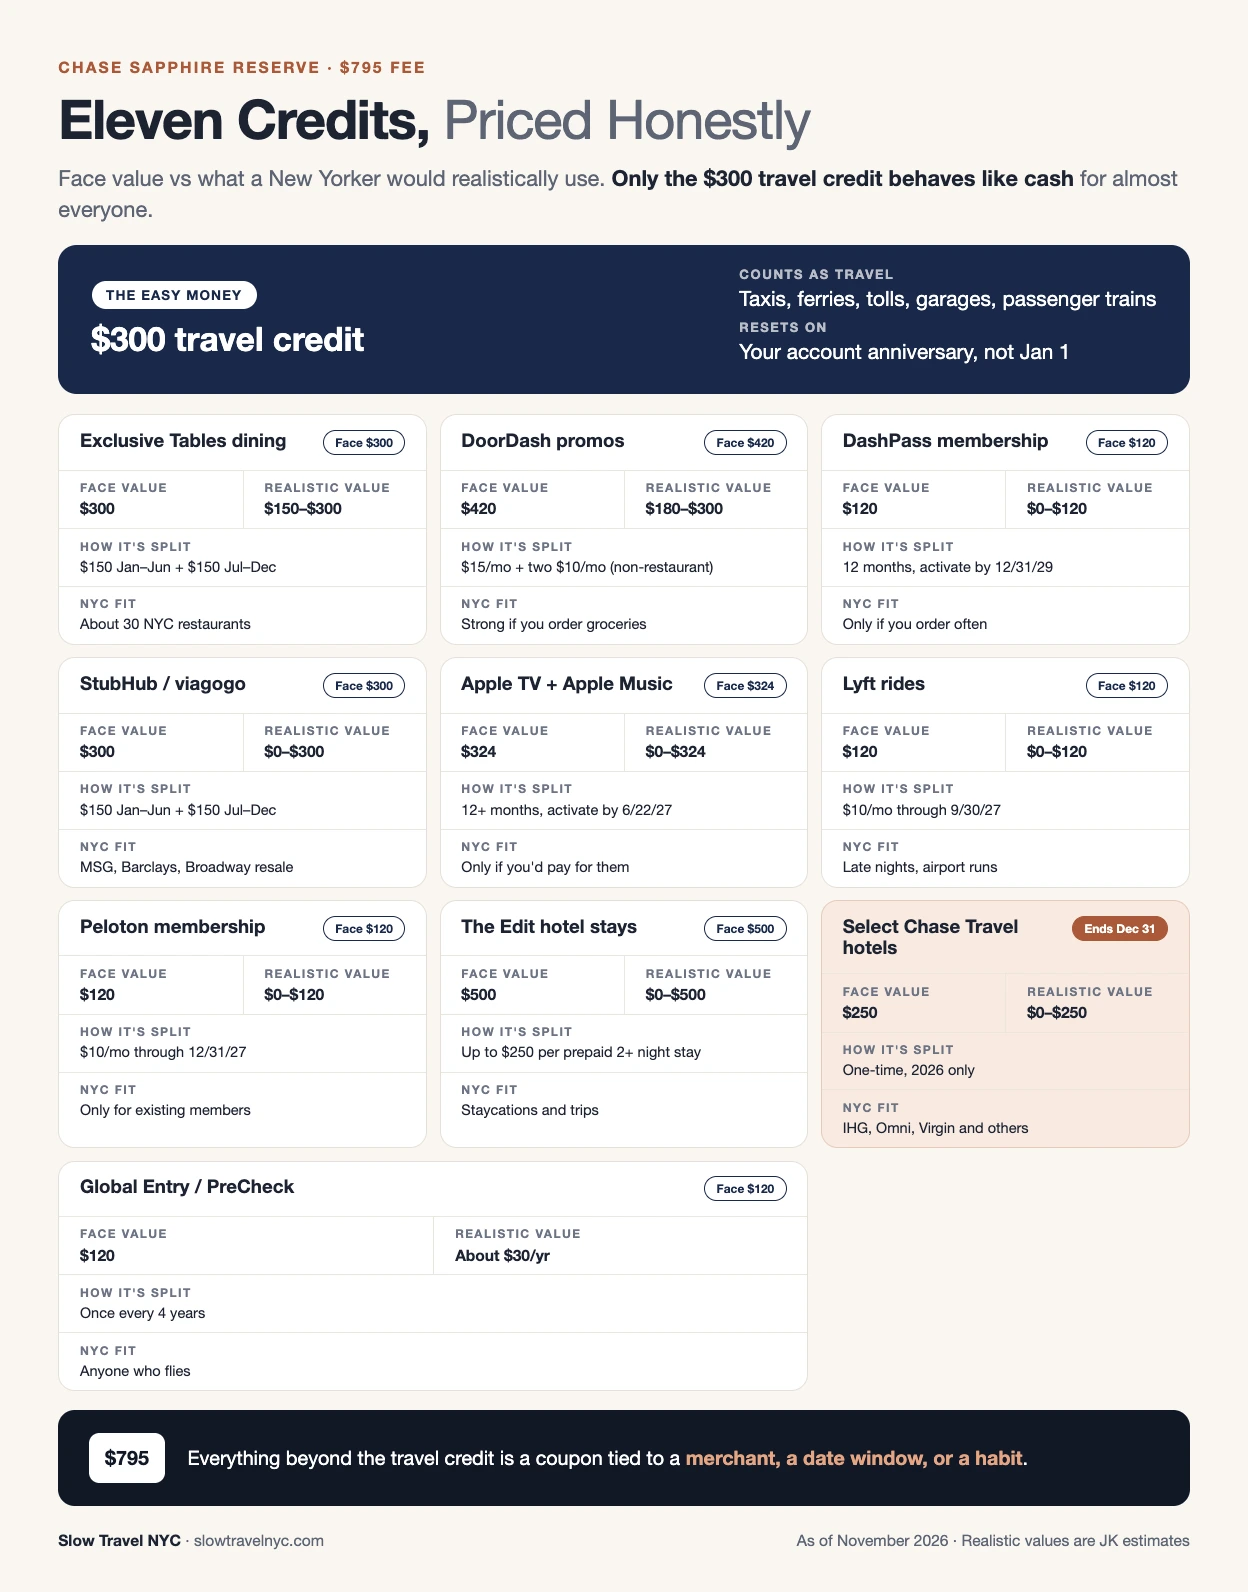
Laid out like this, the Sapphire Reserve credits in NYC fall into two groups. Only one credit, the $300 travel credit, behaves like cash for almost everyone. Everything else is a coupon tied to a merchant, a calendar window, or a habit.
The $300 Travel Credit Is the New Yorker’s Easiest Win
Chase defines the travel category broadly. Its card terms list taxis, limousines, ferries, toll bridges and highways, parking lots and garages, buses, and passenger trains alongside airlines and hotels. For someone who lives here, that means the credit can disappear into ordinary life: a few cab rides home from dinner, a month of garage parking, E-ZPass tolls on a trip upstate, or Metro-North tickets to the Hudson Valley.
Two details matter. First, the credit resets on your account anniversary, not on January 1, so check your own renewal month. Second, purchases covered by the credit don’t earn points, which slightly reduces the value of the earning rates while the credit is being used up.
What I’d verify: Subway and bus taps through OMNY should logically fall under “passenger trains” or “buses,” but I haven’t confirmed how every OMNY charge codes. Look at your statement after a week of commuting before you count on it.
The $300 Dining Credit: Exclusive Tables Only
This is where the card gets more selective. The dining credit works only at restaurants in the Sapphire Reserve Exclusive Tables program on OpenTable, with up to $150 from January through June and another $150 from July through December. The halves do not roll over.
As of a July 2026 check, AskSebby counted 30 NYC restaurants on the list, down from a longer earlier version. The list leans toward places like Don Angie, Estela, l’abeille, and the Dining Room at Gramercy Tavern. It also includes neighborhood spots where $150 covers a meaningful share of an ordinary dinner: Joseph Leonard, Fairfax, Jeffrey’s Grocery, Scarr’s Pizza, and SAPPEISAN. Always check the live Exclusive Tables page on OpenTable before booking, because Chase says the list can change.
The slow-travel angle here is practical. A credit that pushes you toward a tasting menu you wouldn’t otherwise book isn’t saving money; it’s moving it. The better use is a restaurant already on your shortlist, ideally a bar seat on a weeknight when the room is calm. If you’re comparing this with Amex’s Resy-based dining perks, my Michelin restaurants and credit card perks guide covers that side.
Chase’s terms also exclude purchases made through third-party payment processors or delivery platforms. Takeout ordered through an app won’t trigger the credit; paying the restaurant directly at the table should.
DoorDash, Lyft, Apple, Peloton, and StubHub: The Habit Credits
These are the credits that look largest on paper and vary the most in real life.
DoorDash: $15 a month is easy, the $10s take planning
As of October 1, 2026, Chase lists a $15 monthly promo on any qualifying DoorDash order plus two $10 promos each month for non-restaurant orders such as groceries and household items, available through December 31, 2029. The discounts apply to the subtotal only, and any unused value on a single order is forfeited.
For a New Yorker who already orders groceries through DoorDash, this is closer to real money than it sounds. For someone who shops at the corner market and the Union Square Greenmarket, the $10 promos may go unused most months.
Lyft: useful, with a narrow definition of a ride
The $10 monthly Lyft credit applies only to rideshare modes like Standard, Extra Comfort, XL, and Black through September 30, 2027. It doesn’t cover bike or scooter rides, so Citi Bike, which Lyft operates, doesn’t count toward the credit. Chase does say eligible Lyft bike rides and memberships bought in the Lyft app earn 5x points through the same date, which may help if you’re a Citi Bike member, but check how your membership is billed.
Apple, Peloton, and StubHub: value only what you’d buy anyway
Chase values the Apple TV and Apple Music subscriptions at $324 a year. If you already pay for both, that’s close to real savings. If you don’t, the honest value is zero. The same rule applies to the $10 monthly Peloton credit and the StubHub credit, which offers $150 in each half of the year through 2027. A Knicks game or a resale Broadway seat you were already planning to buy is a good use. A ticket bought because the credit was expiring is a purchase, not a savings.
Hotel Credits for Staycations
The Edit credit gives up to $250 back on each prepaid stay of two nights or more booked through Chase’s The Edit collection, up to $500 per calendar year. The Edit stays also come with perks Chase lists as a $100 property credit, daily breakfast for two, and room upgrades and early check-in when available.
For residents, the question is whether you’d ever book two nights in a hotel in your own city or a nearby escape. Some New Yorkers do, especially for a birthday, a parent visit, or a quiet weekend away from a loud apartment. Prepaid rates through a portal can run higher than booking direct, so compare the real total, including NYC hotel taxes, before treating the credit as a discount. My Amex Fine Hotels + Resorts guide uses the same approach for The Plaza and The Carlyle.
One 2026-only extra: Cardholders also get a one-time $250 credit on prepaid stays of at least two nights at select brands booked through Chase Travel in 2026, including IHG, Montage, Pendry, Omni, Virgin Hotels, Minor, and Pan Pacific, per AwardWallet’s guide to the credit. In New York, that could mean a Kimpton or InterContinental property, Omni Berkshire Place, or Virgin Hotels New York City. Look for the eligibility label in Chase Travel. It ends December 31, 2026.
Chase Sapphire Reserve for NYC Residents: Three Profiles
The math depends far more on habits than on income. These are my estimates, using only the credits each profile would realistically use, before points and lounge visits.
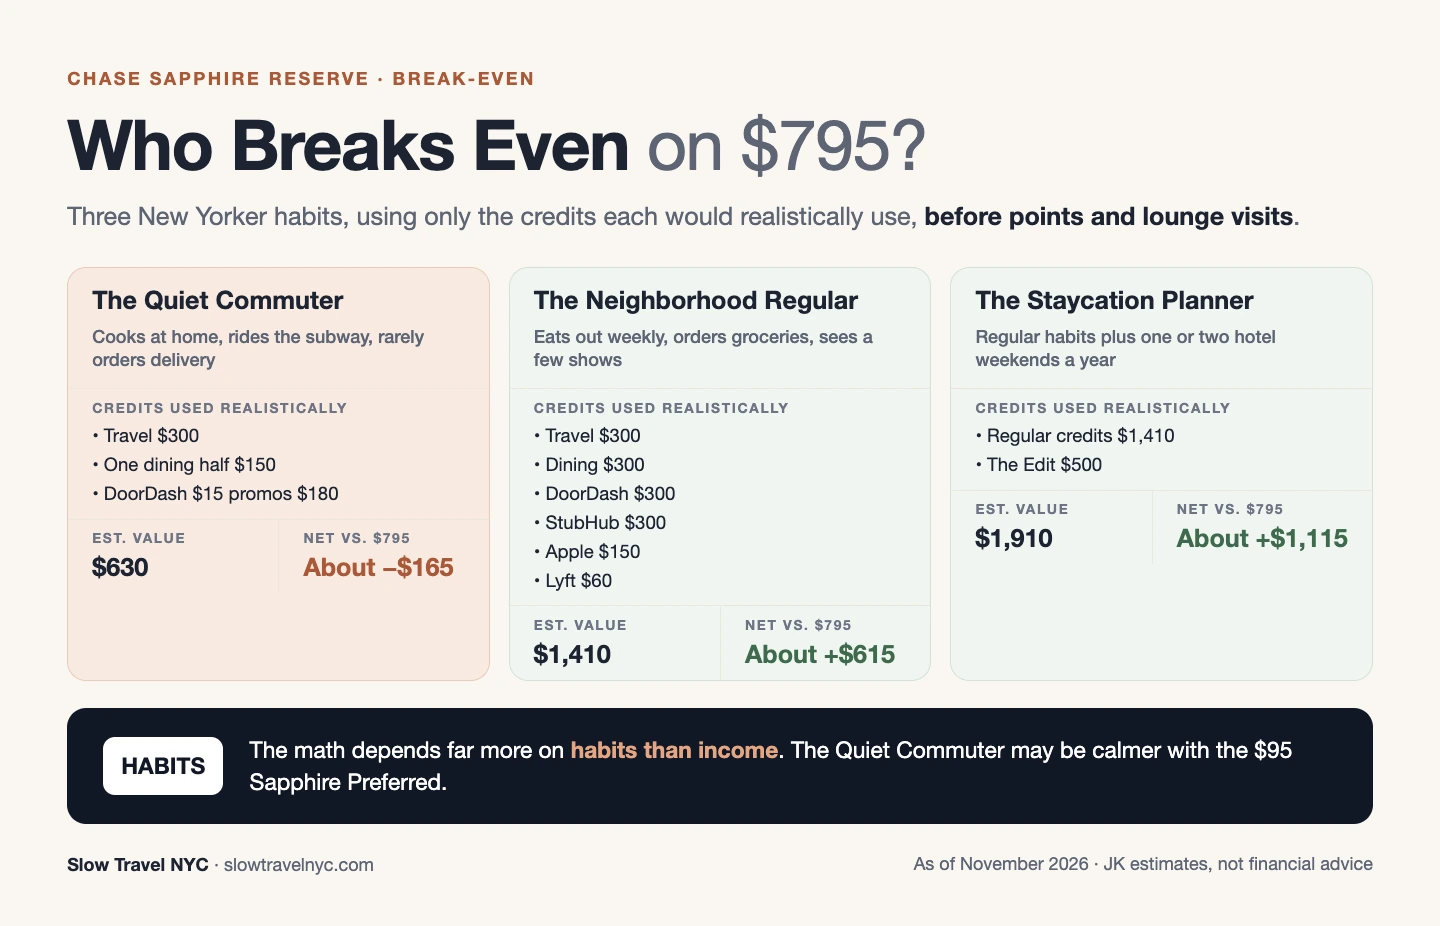
The Quiet Commuter is the most “slow” New Yorker on this list, and the card works least well for that life. That isn’t a flaw in the person. It’s a reminder that premium cards reward a specific pattern of spending, and the pattern isn’t always yours.
If you want to see how these credits change the cost of an actual trip, plug the numbers into the NYC Trip Budget Calculator, and use the NYC Tip & Tax Calculator when you’re estimating restaurant checks against the $150 dining halves.
Reality Check: The Limits for New Yorkers
- It’s a calendar job. Two semiannual credits, two monthly DoorDash promos, one monthly Lyft credit, and one anniversary-year credit all reset on different schedules. If you don’t enjoy tracking them, the value shrinks fast.
- New York residents get slightly weaker coverage. Chase’s card terms say that for New York residents, auto rental coverage inside the U.S. is secondary to personal auto insurance, purchase protection lasts 90 days instead of 120, and lost luggage reimbursement is capped at $2,000 per bag and $10,000 per trip.
- The restaurant list moves. About 35 NYC and nearby restaurants dropped off the Exclusive Tables list between versions, according to AskSebby’s July 2026 comparison.
- Points earning is ordinary off-travel. Groceries, rent, and most everyday spending earn 1x. If your goal is rent rewards, see my Manhattan rent rewards and Bilt guide.
- Authorized users are no longer cheap. At $195 each, adding a partner only makes sense if they’ll use the lounge access and their own spending.
What to Do Before December 31, 2026
If you already carry the card, November and December are when the 2026 credits either get used or disappear.
- Book one Exclusive Tables dinner to use the July–December $150 dining credit.
- Use the second StubHub half on an event you were already planning to attend, such as a holiday show or a winter game.
- Check the $250 select-hotel credit. If a two-night stay at an eligible brand is already in your plans, book it through Chase Travel before year-end.
- Claim this month’s DoorDash and Lyft credits, since monthly promos never carry over.
- Note your renewal month. If your annual fee posts soon, decide now whether the coming year matches the Neighborhood Regular profile or the Quiet Commuter one.
For winter flights, the card’s trip delay coverage applies after six hours or an overnight delay, up to $500 per traveler. My NYC trip delay insurance guide explains how to file if a snowstorm grounds you.
Frequently Asked Questions
Does the Sapphire Reserve travel credit work on NYC taxis and the subway?
Chase’s travel category includes taxis, buses, passenger trains, ferries, tolls, and parking garages, so yellow cabs and Metro-North tickets should qualify. Subway and bus taps through OMNY likely fall under that definition too, but check your statement to confirm how they code before relying on it.
Can I use the $300 dining credit on DoorDash or takeout?
No. The dining credit applies only to purchases made directly with restaurants in the Sapphire Reserve Exclusive Tables program on OpenTable. Chase’s terms exclude orders through delivery platforms and third-party payment processors.
Is the Chase Sapphire Reserve worth it for NYC residents who rarely fly?
It can be, but only if you’d naturally use the travel credit, both dining halves, and most of the DoorDash promos. Without those three, the remaining credits depend on subscriptions and habits that many New Yorkers don’t have.
What happens to unused Sapphire Reserve credits?
They expire. The dining and StubHub credits reset every six months, the DoorDash and Lyft credits reset monthly, and the travel credit resets on your account anniversary. None of them roll over.
Should I downgrade to the Sapphire Preferred instead?
If the credits don’t fit your life, the Sapphire Preferred has a $95 annual fee as of November 2026 and keeps you in Chase’s points ecosystem. You’d give up the Reserve’s credits, lounge access, and higher earning on Chase Travel. Call Chase before your renewal to ask about product change options.
The Slow Answer
The Sapphire Reserve isn’t really a luxury card for New Yorkers. It’s a set of small, scheduled rebates on things city people already do: take a cab, order groceries, book dinner, buy a ticket. If those things are already part of your week, the $795 fee can disappear quietly.
If they aren’t, the card asks you to change your routine to justify it, and that’s the opposite of slow living. Price each credit at what you’d spend anyway, and the right answer usually becomes obvious within a few minutes.